Responsible lending: what it means for Australian borrowers
Australian credit law still turns on whether a contract is unsuitable. Lenders must inquire, and often verify, before they offer many products — with different settings for ADIs and for buy now, pay later. General information, not legal advice.
Published 9 January 2026 · Updated 20 October 2026 · 9 min read
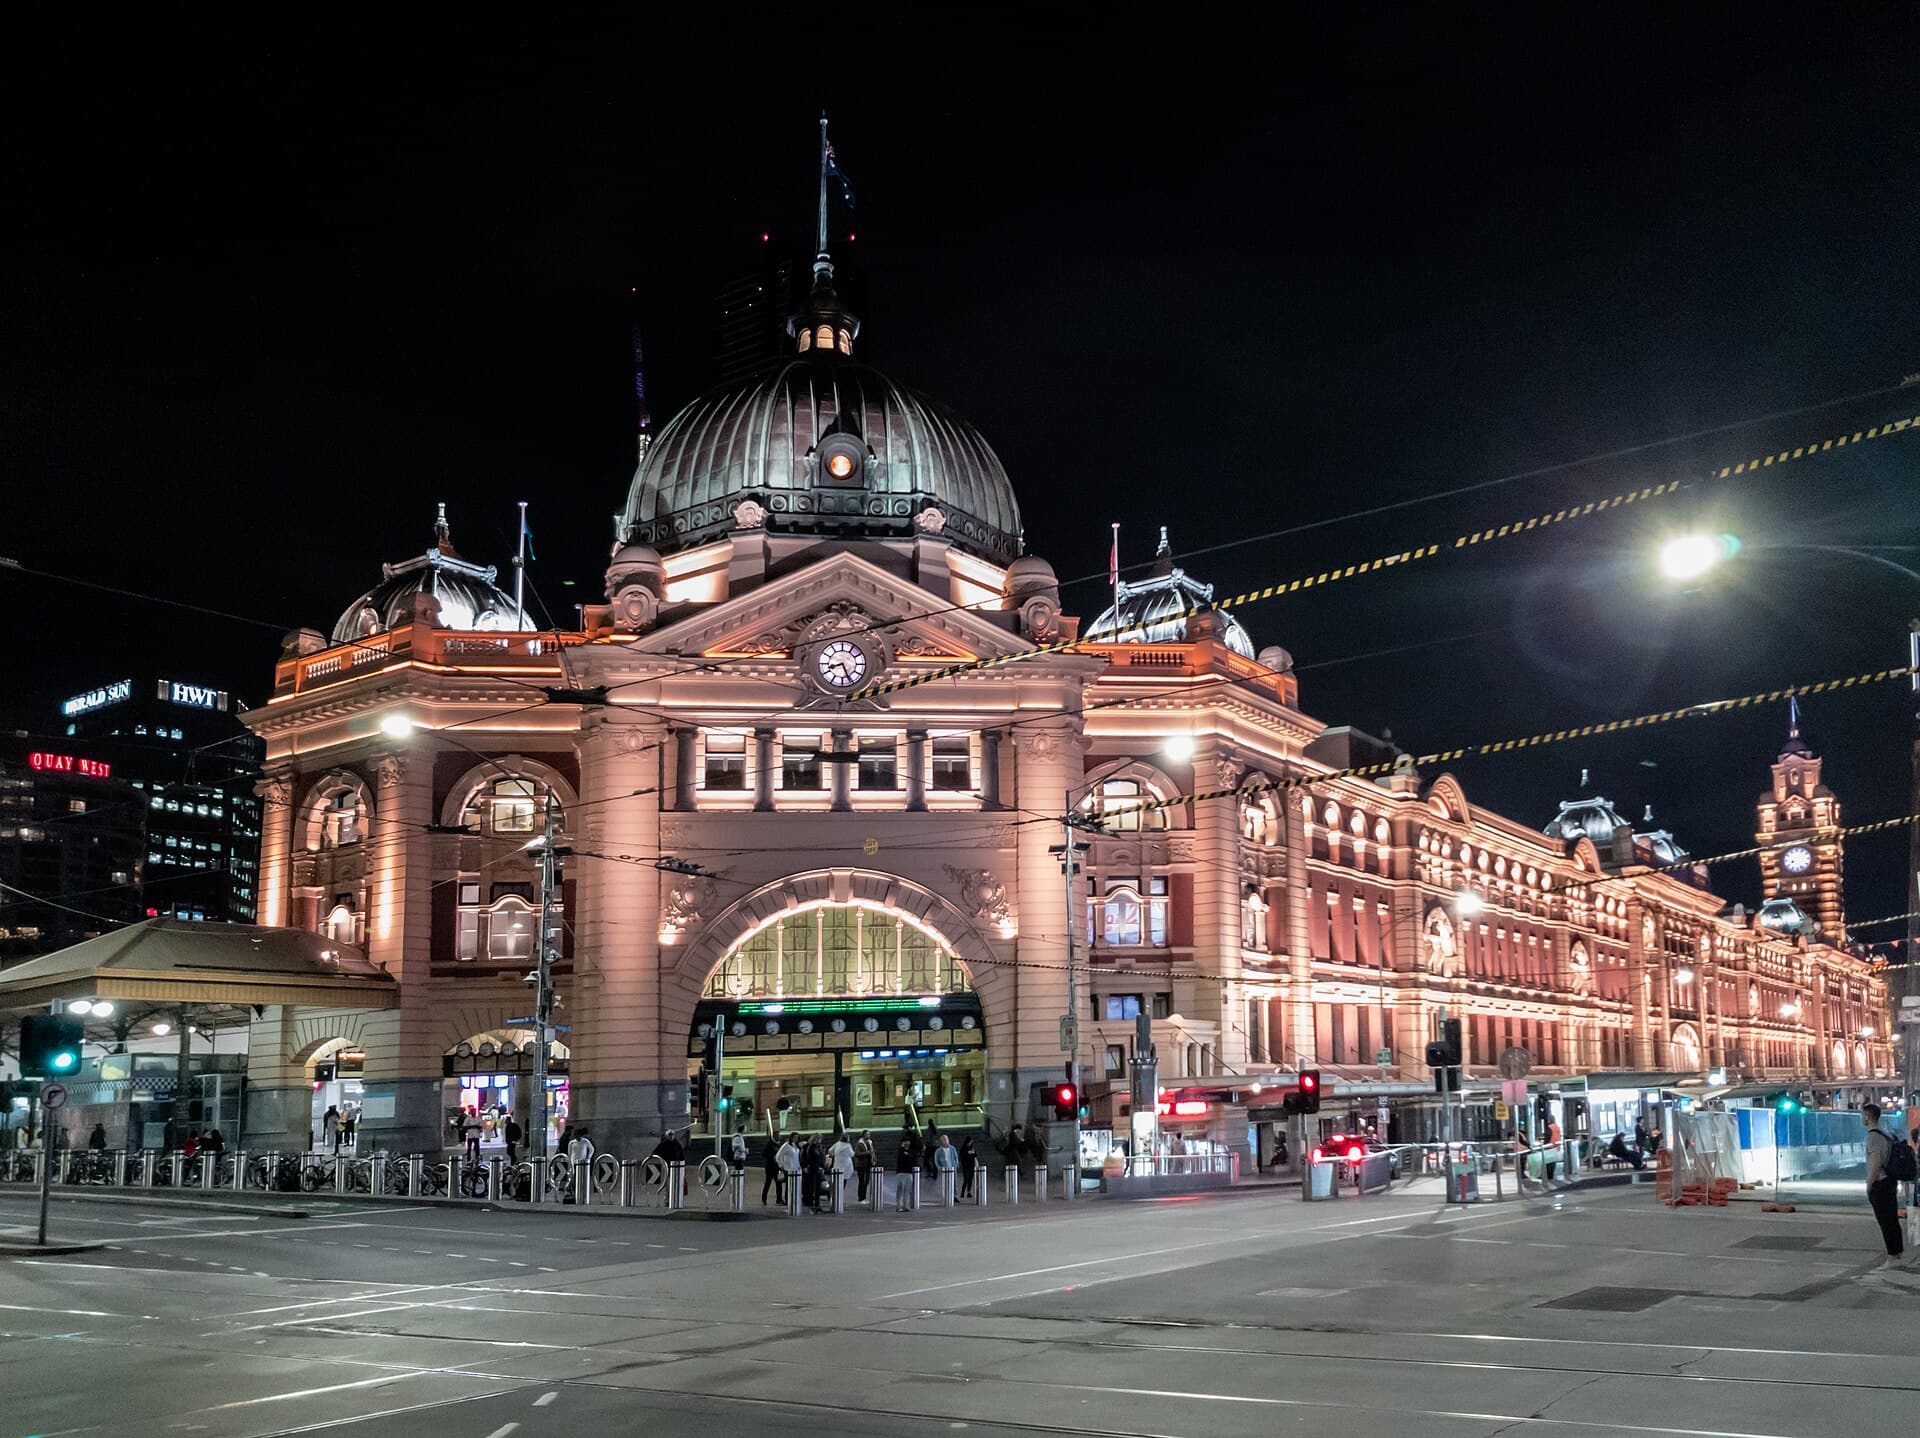
Photo: Dietmar Rabich. CC BY-SA 4.0. Source. See all image credits.

“Responsible lending” is a phrase that gets used as if it were a character reference. In Australian law it is a process and a prohibition. A licensed credit provider is not supposed to enter a credit contract, or increase a limit, if the contract would be unsuitable for the consumer. Unsuitable has a definition. It is not the same as “I later wished I had not signed”.
The statute is the National Consumer Credit Protection Act 2009 (the NCCP Act). The National Credit Code sits as Schedule 1 to that Act and does the hardship, disclosure and default-notice work. ASIC is the conduct regulator for credit licensees. Plenty Credit is not a law firm. What follows is general information about the public shape of those rules, including the 2021 changes for banks and the 2025 settings for buy now, pay later. It is not an opinion on your particular loan.
The old Plenty Credit Co-operative in Lalor never had to explain Regulatory Guide 209 to a member at the counter. It did have to decide whether a contract fitted. That habit is the one worth keeping when you sit at Flinders Street with a pre-approval SMS.
What does responsible lending actually require?
For credit licensees that still sit under Chapter 3 of the NCCP Act, the familiar sequence is:
- make inquiries about the consumer’s requirements and objectives
- make inquiries about the consumer’s financial situation
- take reasonable steps to verify that financial situation
- assess whether the contract is unsuitable
- not offer, suggest, or enter the contract (or a credit-limit increase) if it is unsuitable
Those steps are the “assess and verify” idea ASIC has spent years describing. They apply, in slightly different wording, to credit assistance (brokers) as well as to credit providers. A broker who suggests a loan and a lender who writes it can both be in the frame.
The duty is not a guarantee that you will find the repayments easy in three years. It is not a promise that the interest rate is kind. It is a prohibition on writing a contract that, at the time of assessment, fails the unsuitability tests on the information the licensee has or should have.
If you are the person applying, your job is narrower and still important: answer the questions accurately, provide the documents, and do not “help” the application by omitting a BNPL account or a second job that just ended. False information is how assessments go wrong in both directions.
What is an unsuitable credit contract?
The NCCP Act treats a contract as unsuitable if, at the time of the assessment, it is likely that:
- the consumer will be unable to comply with the financial obligations, or could only comply with substantial hardship, or
- the contract will not meet the consumer’s requirements and objectives
Substantial hardship is a legal phrase, not a mood. ASIC has long said that being able to meet repayments only by selling your home, for example, is the kind of outcome the test is meant to catch. Going without discretionary spending is not automatically hardship in that sense. Going without food, or being set up to miss rent, is closer to the territory.
The requirements and objectives limb is the one people forget. A five-year personal loan used to fund a purchase you said you needed for three months can fail this limb even if the repayment “fits” a spreadsheet. A secured car loan when you asked for unsecured credit, or a card with an annual fee when you said you wanted no fees, can raise the same question. It is not a rewrite button for buyer’s remorse. It is a check that the product matches what you told them you wanted.
A contract can also be unsuitable in more specific ways for particular product classes. Small amount credit contracts have extra rules, including income tests. Those sit on top of, not instead of, the general idea.
Unsuitable is assessed when the licensee assesses, not when you reread the statement in winter. A later job loss is usually a hardship problem, not proof that the original assessment was unlawful. The two conversations get mixed in complaints. They are different files.
What inquiries and verification is a lender supposed to do?
Inquiries are questions: what the credit is for, how long you need it, what you earn, what you spend, what you already owe, who depends on you. Verification is evidence: payslips, Centrelink statements, tax returns, bank-account records, a credit report.
ASIC has never said that every loan requires the same bundle. A small, short facility and a large, long one are not the same risk. The theme in Regulatory Guide 209 (RG 209) — ASIC’s responsible-lending guide — is that inquiries and verification should be proportionate to the product, the consumer, and the risk of the contract being unsuitable. A licensee is not entitled to skip the work because a score looks tidy. A licensee is not required to audit your life as if it were a homicide investigation.
What borrowers actually see:
- income evidence that matches the application, not a number typed to clear a filter
- a look at existing debts, including other cards and, increasingly, BNPL
- living-expense figures that are not a fantasy “$50 a week on food” the website suggested
- a bureau file from Equifax or Experian — which body is the lender’s choice; see the bureau comparison
If a lender asks for more documents, that is often the verification step working. If a lender asks for nothing and offers a large limit the same afternoon, that is a fact you may later want in writing. It is not, by itself, a win.
Scalping a living-expense benchmark and ignoring what your statements show has been a recurring ASIC concern. If you are told to “just use the average”, you are allowed to insist the file reflect your rent in Epping, not a national mean.
What does ASIC’s RG 209 still tell borrowers?
RG 209 is written for licensees. Borrowers can still read it as a map of what “good enough” was supposed to look like.
Themes that have survived the edits:
- understand purpose, amount and term
- understand income and expenses, including irregular income
- verify what can reasonably be verified
- do not ignore red flags (a new high-rate loan used to pay other high-rate loans; a consumer who is already in hardship; a mismatch between stated rent and the address)
- record the assessment so it can be reviewed later
- do not provide a contract that is unsuitable, even if the consumer wants it
RG 209 is not a script you can recite at a branch to force an approval. It is also not a relic. ASIC has updated it as the law around ADIs changed, and it remains the reference for licensees who still have the statutory duties.
If a complaint later goes to AFCA, the file that shows what was asked, what was provided, and what was assessed is more useful than a speech about “responsible lending” as a slogan. Keep copies of the application, the documents you uploaded, and any credit guide you were given.
Do banks still have the same responsible-lending duties as other lenders?
Not always. This is the paragraph that outdated blog posts get wrong.
In 2021, Parliament removed many authorised deposit-taking institutions — banks, credit unions, building societies — from the NCCP Act responsible-lending obligations for a wide range of credit contracts. Those ADIs are instead expected to lend under APRA prudential standards, particularly the credit-risk standard known as APS 220, and under their own responsible-lending-style policies. ASIC’s consumer-protection role did not vanish. The specific Chapter 3 “unsuitable contract” pathway is not the same for every ADI product.
Non-ADI credit licensees — many finance companies, some specialist car lenders, payday lenders, and others — generally still have the NCCP responsible-lending obligations, unless a specific exemption applies.
For you, the practical translation is:
- do not assume a big-four home loan was assessed under the same statutory test as a non-bank personal loan
- do not assume a non-bank has no duties
- read the credit guide and the assessment rights that still apply to your product
- if you ask for a copy of the assessment, ask in writing and keep the request
How to compare personal loans and how to read a credit contract are the shopping documents. Responsible lending is the conduct layer behind them.
How do the rules change for buy now, pay later?
From 10 June 2025, many BNPL arrangements are low cost credit contracts (LCCCs) under the national credit laws. Providers of those products generally need an Australian credit licence, AFCA membership, hardship processes, and modified responsible-lending obligations. ASIC’s Regulatory Guide 281 is the specialised guide for that product class.
Modified means what it says. It is not “no assessment”. It is also not always a full home-loan-style verification. The design was to pull BNPL out of the unregulated gap without pretending a $180 clothing order is a mortgage. Our longer piece — buy now pay later in Australia: how the new rules work — sits with that detail.
What has not changed is the household arithmetic. Four BNPL ledgers due in the same week are still four ledgers. A provider that now has to think about unsuitability is not a provider that has made the instalments free. If you cannot meet them, hardship is the conversation, including on a regulated BNPL account.
What can you do if you were given a loan you could not afford?
First, deal with this month. A responsible-lending complaint does not pause rent. Use the budget, the National Debt Helpline on 1800 007 007, and a hardship request on the contract you have.
Then, if you believe the contract was unsuitable at the time it was written:
- Write to the credit provider’s complaints address. State the product, the date, what they asked for, what you provided, and why the contract did not meet the tests. Attach the application pack if you still have it.
- Ask for the assessment and the credit guide.
- Use internal dispute resolution. ASIC’s RG 271 is the complaints-handling standard.
- If that fails and the provider is a member, take the complaint to AFCA. AFCA can look at responsible-lending issues. It is free for the consumer. It is not a court.
- Keep making whatever you have said you can pay, if you still can.
A later default is a separate, uglier fact. What happens if you default is that sequence. Responsible lending can still be relevant to how the account should be treated. It does not delete a true history by itself. Anyone who says otherwise is usually selling credit repair.
MoneySmart’s pages on loans and borrowing remain the government plain-English layer. The statute is the NCCP Act. The valley tone, for a journal that grew out of a member-owned co-operative, is simpler still: a contract should have been capable of being lived with when it was signed. If it was not, there is a process. If it was, and life changed, there is a different process, and that process is hardship.
More of this series lives under consumer rights and under personal loans. Read the contract before you sign it. The guide for that job is next to this one.
Frequently asked questions
What is responsible lending in Australia?
It is a set of duties in the National Consumer Credit Protection Act that stop a licensee offering a credit contract that is unsuitable for the consumer. Unsuitable generally means you could not meet the obligations, or could only meet them with substantial hardship, or the contract does not meet your requirements and objectives.
Do banks still have to assess whether a loan is unsuitable?
Authorised deposit-taking institutions were removed from some National Credit Act responsible-lending obligations in 2021, and are supervised under APRA’s lending standards. Many non-ADI lenders still sit under the Act. The product in front of you is what matters.
Does buy now, pay later have responsible-lending rules now?
From 10 June 2025 many BNPL products are low cost credit contracts with modified responsible-lending obligations, which ASIC discusses in Regulatory Guide 281. That is not always a full home-loan assessment.
Questions about this guide? Contact the Plenty Credit desk or read our editorial standards.
More in Consumer rights
Identity theft and your credit file
Fraudulent accounts and mixed files look similar on a credit report and are different problems. Freeze or ban the file, use IDCARE, report to police where needed, and correct Equifax and Experian in writing. General information, not legal advice.
9 min read · 29 July 2026
How to read a credit contract before you sign
Before you accept a personal loan, car loan or card, read the amount, rate, comparison rate, fees, default clauses, any security, and add-on insurance. Cooling-off is limited. General information, not legal advice.
9 min read · 18 June 2026
Credit repair companies in Australia: what ASIC warns about
You can dispute genuine errors on Equifax and Experian for free. No one can lawfully delete a true default overnight. ASIC and CreditSmart have warned about repair firms that over-promise or charge upfront. General information, not advice.
9 min read · 6 May 2026