How to compare personal loans in Australia
A comparison rate is only one column. Australian personal loans also differ on fees, term, fixed versus variable pricing, early repayment and whether you even qualify for the number on the billboard.
Published 14 January 2026 · Updated 16 October 2026 · 9 min read
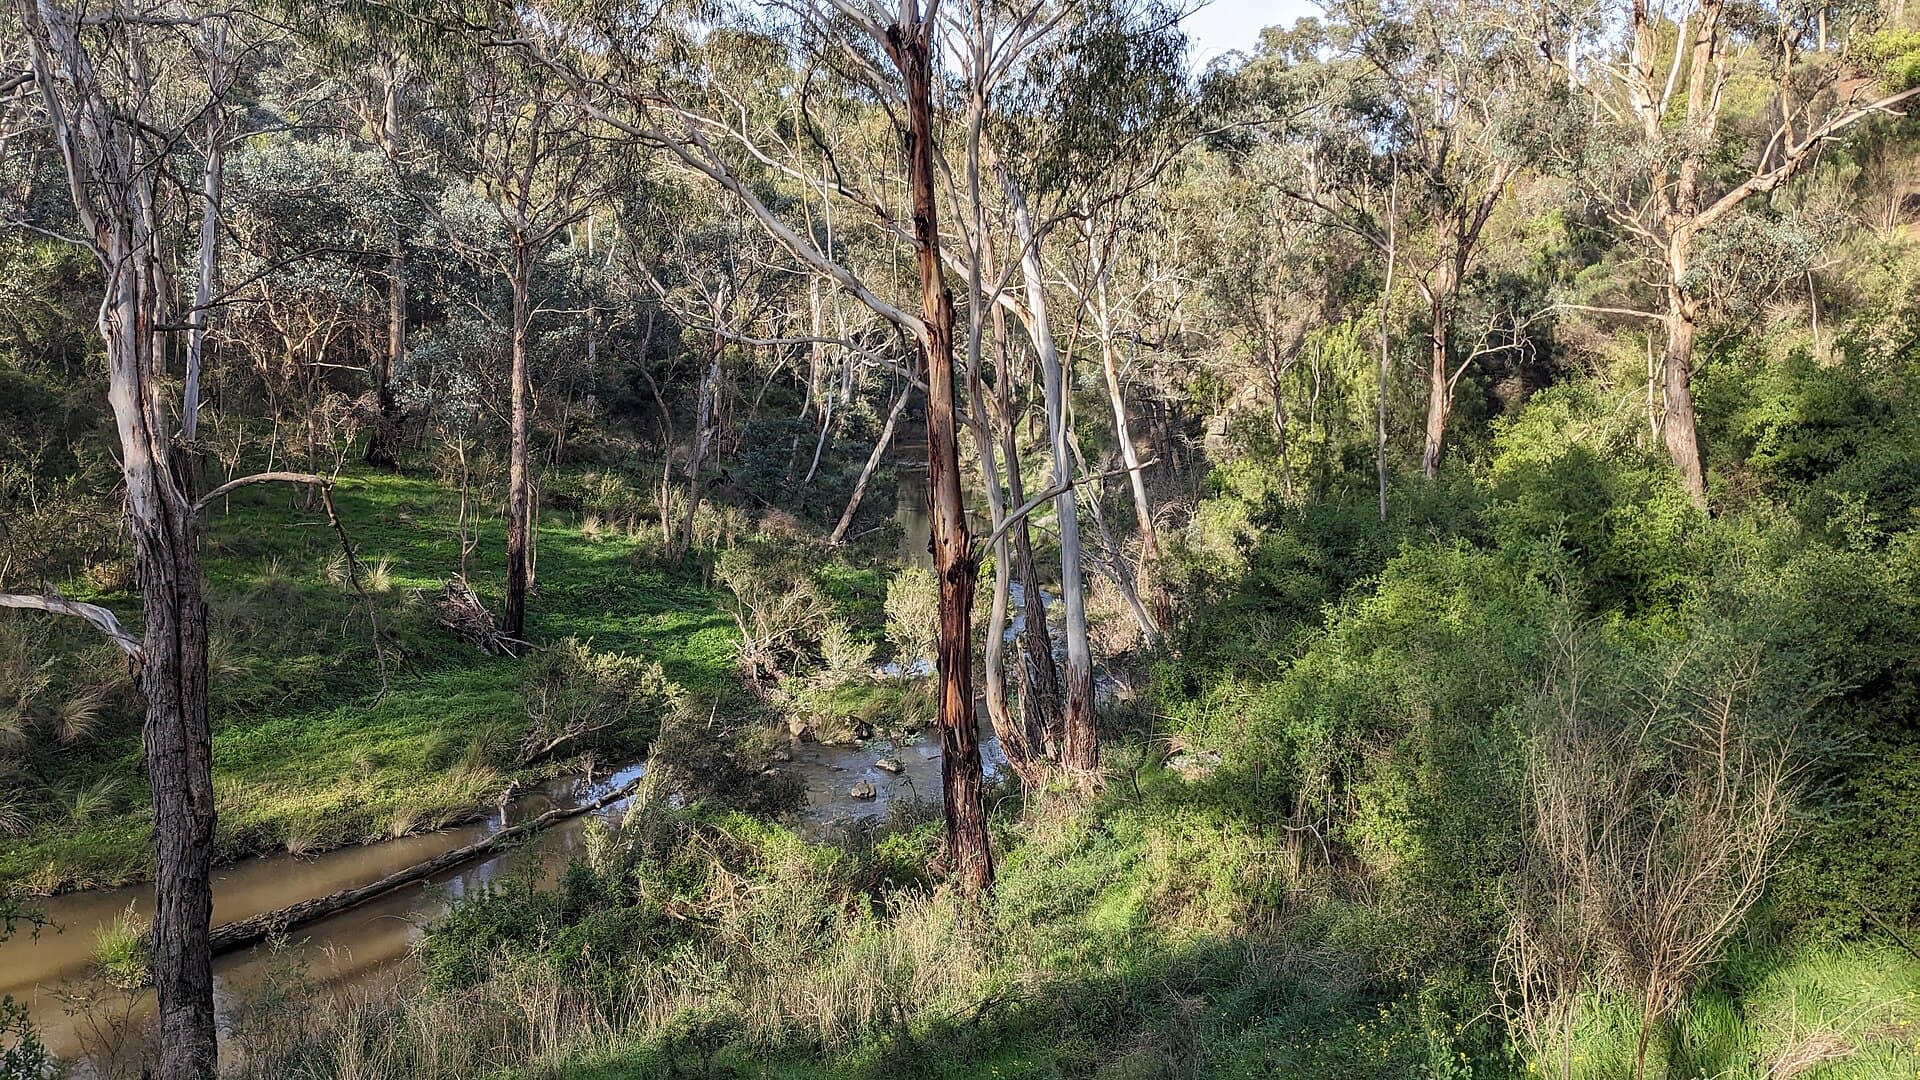
Photo: Philip Mallis. CC BY-SA 2.0. Source. See all image credits.

The number on a personal-loan billboard is an invitation, not a quote. In Australia the advertised rate is usually the lowest figure a lender is prepared to print for a borrower who fits a tight box. Everyone else is priced later, after documents, a credit file and a conversation about expenses.
Plenty Credit’s old co-operative counter in Lalor used to put two printouts side by side and talk through the fees before anyone mentioned the interest rate. That habit still beats a colour-coded ranking. This guide is a method for comparing personal loans as products, not as slogans. It is general information, not a recommendation to borrow.
ASIC’s MoneySmart page on personal loans is the cleanest official companion. The legal frame sits in the National Credit Code, which is Schedule 1 to the National Consumer Credit Protection Act 2009.
What should you compare on a personal loan besides the interest rate?
Start with five facts that survive marketing:
- Amount — the cash you would actually receive, after any establishment fee that is added to the balance.
- Term — how many months the contract expects you to pay. A longer term shrinks the repayment and grows the interest.
- Rate type — fixed for a period, variable, or a split that is neither as simple as the heading.
- Fees — establishment, monthly or annual, unpaid-repayment, redraw, and anything labelled “optional” that is ticked by default.
- Exit rules — whether you can repay early, and what that costs.
Only then look at the rate. Two loans at “from 8.99% p.a.” can cost different amounts of money because one loads a $400 establishment fee onto a three-year term and the other does not.
Write those five facts for each product on a single page. The old credit-union habit was a lined pad. A spreadsheet is fine. The point is to stop comparing a repayment on a radio ad with a repayment on a broker’s calculator that assumed a different term.
What is the difference between the advertised rate and the comparison rate?
The advertised rate is the interest rate the lender wants you to remember. The comparison rate is a second percentage, required in many advertisements, that folds in most known fees and expresses the result as a single figure.
They exist because a cheap-looking rate plus a thicket of fees is an old trick. The comparison rate is the law’s attempt to put that trick on the same line. It is not magic, and it is not calculated on your loan unless the example happens to match. The standard television example — a large amount over a long term — is a poor proxy for a $12,000 unsecured loan. That gap is the whole subject of what a comparison rate is and why it matters.
Use both numbers. If the advertised rate and the comparison rate sit far apart, the fees are doing real work. If they sit close together, fees may be light or the example may be hiding them. Open the fee schedule either way.
How do fees and the loan term change the real cost?
Fees are not a rounding error on a small personal loan. A $250 establishment fee on a $5,000 loan is 5 per cent of the principal before a day of interest has run. Monthly account fees do the same thing more quietly.
The term is the other lever people under-read. Stretching a loan from three years to seven can make the weekly figure look civilised and add years of interest. MoneySmart’s calculators exist for this reason: they show total interest, not only the repayment that fits a payslip.
A practical comparison, still not advice for any household:
- Fix the amount you would actually borrow.
- Fix a term you could finish earlier if you chose to, not the longest term on the menu.
- Add every fee you can find in the credit guide and the contract.
- Ask what happens if you pay the loan out in half the time.
That last question belongs with early-repayment rules, not with the comparison-rate footnote.
Fixed versus variable personal loan rates
A fixed rate stays put for the fixed period. The repayment is easier to calendar. The trade is that breaking the fix — refinancing, selling a secured car, paying the loan out after a windfall — can trigger a break cost or an early-repayment fee. Read that clause before you enjoy the certainty.
A variable rate can move. It may fall; it may not. Budgeting against a variable personal loan means leaving room for a higher repayment, not assuming today’s figure is a floor.
Some lenders advertise a “fixed” personal loan that is fixed for a shorter period than the full term, then reverts. That is not dishonest if it is written down. It is easy to miss in a comparison table that only has room for one percentage.
Neither type is morally better. They are different risks. The comparison is: can you live with the repayment if the variable rate rises, and can you live with the exit fee if the fixed loan needs to end early?
Can you repay a personal loan early in Australia?
Often yes. Not always cheaply. The National Credit Code gives consumers rights around payout figures and early repayment on many regulated contracts, but it does not make every fee vanish.
Ask, in writing if the website is vague:
- Is there an early-repayment or termination fee?
- On a fixed-rate loan, is there a break cost, and how is it calculated?
- Are prepaid interest or remaining monthly fees clawed in?
- Will extra repayments reduce the term, reduce the next repayment, or sit in a redraw account?
Redraw and “offset” features on personal loans are less common than on home loans and are easy to misunderstand. If the feature exists, check whether using it is free, whether redrawn money is treated as a new advance, and whether the comparison rate assumed you would never touch it.
A loan you cannot leave is a different product from a loan you can finish after a tax return. Tables that hide the exit column are not comparing the same thing.
What eligibility rules quietly decide the price you are offered?
The advertised rate is commonly a “from” rate. The rate you are offered is a risk price. Lenders look at income, existing debts, employment type, the purpose of the loan, and the file held by Equifax or Experian. Two people clicking the same tile can be shown different numbers, or one can be declined.
Before you treat a ranking as real:
- Read the lender’s published eligibility notes — minimum income, citizenship or residency, employment duration, and whether casual or self-employed applicants are considered at all.
- Pull your own files first. How to get a free credit report is the starting point; how to improve a credit score is the slower follow-up if the file is messy.
- Treat “pre-qualified” and “indicative” quotes as marketing until you know whether the look at your file was hard or soft. Hard versus soft enquiries explains which clicks leave a mark.
Eligibility is also why a secured loan can look cheaper on a billboard and still be unavailable if you have no acceptable asset. That fork is covered in secured versus unsecured personal loans.
Are comparison websites independent?
Some are owned by listed companies whose revenue is paid by lenders. Some are owned by the lenders themselves and dressed as a “help me choose” tool. A table can still be a useful catalogue of products that exist. It is not a finding by a regulator.
Conflicts to watch:
- Pay-per-click or pay-per-loan — the top row may be the highest commission, not the lowest comparison rate.
- Incomplete panels — credit unions, small ADIs and community lenders often do not buy the slot. The former Plenty Credit Co-operative would not have appeared on most modern widgets.
- Default settings — a calculator that assumes a seven-year term and includes add-on insurance will flatter a weekly repayment.
- Soft language about “partners” — read the financial services guide and the credit guide, not the badge that says “we compare 30 lenders”.
If you use a site, export or screenshot the assumptions. Then open each lender’s own credit guide and the proposed contract. How to read a credit contract before you sign is the document-level companion to this shopping guide.
MoneySmart’s personal-loan material does not rank brands. That is the point of a public explainer.
How to organise a side-by-side comparison without applying five times
A cluster of applications in a fortnight is exactly what a credit file records as hunger for credit. You do not need five formal applications to compare five products.
A calmer sequence:
- Decide the amount and a term you could actually finish. If the amount is really a car, read what to check on a car loan before you treat it as a generic personal loan.
- List three or four lenders you are eligible for on paper, including at least one that is not paying for the comparison-site tile.
- Collect the advertised rate, comparison rate, fees, early-repayment rules and security requirements.
- Use a soft-enquiry or eligibility check only where the lender states, in writing, that it will not record a hard enquiry.
- Apply once, or twice if the first outcome is a genuine mismatch — not seven times on a Sunday night.
If repayments already will not fit an existing loan, stop comparing new ones and read how to ask a lender for hardship help. Shopping for a second product is not a hardship variation.
When you are ready for paperwork rather than tables, how to apply for a personal loan walks through documents, timelines and why the quoted rate still moves after the advertisement.
The Plenty River at South Morang does not care which lender you pick. Households do. Compare the contract you would sign, not the rate you were first shown. If a website will not show the fees until after you apply, that is information too.
Frequently asked questions
Is the lowest advertised personal loan rate the cheapest loan?
Not necessarily. Establishment fees, monthly fees, a longer term and a comparison rate calculated on a different example can all make a “cheaper” rate cost more. Eligibility can also push you off the advertised figure entirely.
Should I apply to several lenders so I can compare offers?
Comparing features on paper does not require a full application. Each formal application can add a hard enquiry to your credit file. Use published criteria and, where a lender offers it, a soft-enquiry estimate first.
Are comparison websites independent?
Many are paid when you click or when a loan is written. That does not make every table useless, but it does mean the order of lenders is not a public-interest ranking. Read the disclosure and still open the contract yourself.
Questions about this guide? Contact the Plenty Credit desk or read our editorial standards.
More in Personal loans
Personal loans vs credit cards vs buy now pay later
Three ways to pay later, three different clocks. Personal loans, credit cards and buy now pay later do not cost the same, last the same, or look the same on an Australian credit file — and stacking them is how a small gap becomes a file.
9 min read · 30 June 2026
Car loans in Australia: what to check before you sign
The weekly figure on the windscreen is not the cost of the car. Dealer finance, balloon payments, insurance add-ons, used-car history and the PPSR all change what you drive away owing.
9 min read · 27 May 2026
What is a comparison rate and why it matters
A comparison rate is a legal percentage, not a marketing badge. It folds most known fees into a single figure — but the $150,000 over 25 years example on many ads is the wrong picture for a personal loan.
9 min read · 19 April 2026