Payday loans and small amount credit contracts explained
Australian payday loans are regulated as small amount credit contracts, with fee caps, a 10 per cent income test from June 2023, and comparison rates that look alarming because the term is short. General information only.
Published 21 April 2026 · Updated 18 October 2026 · 9 min read
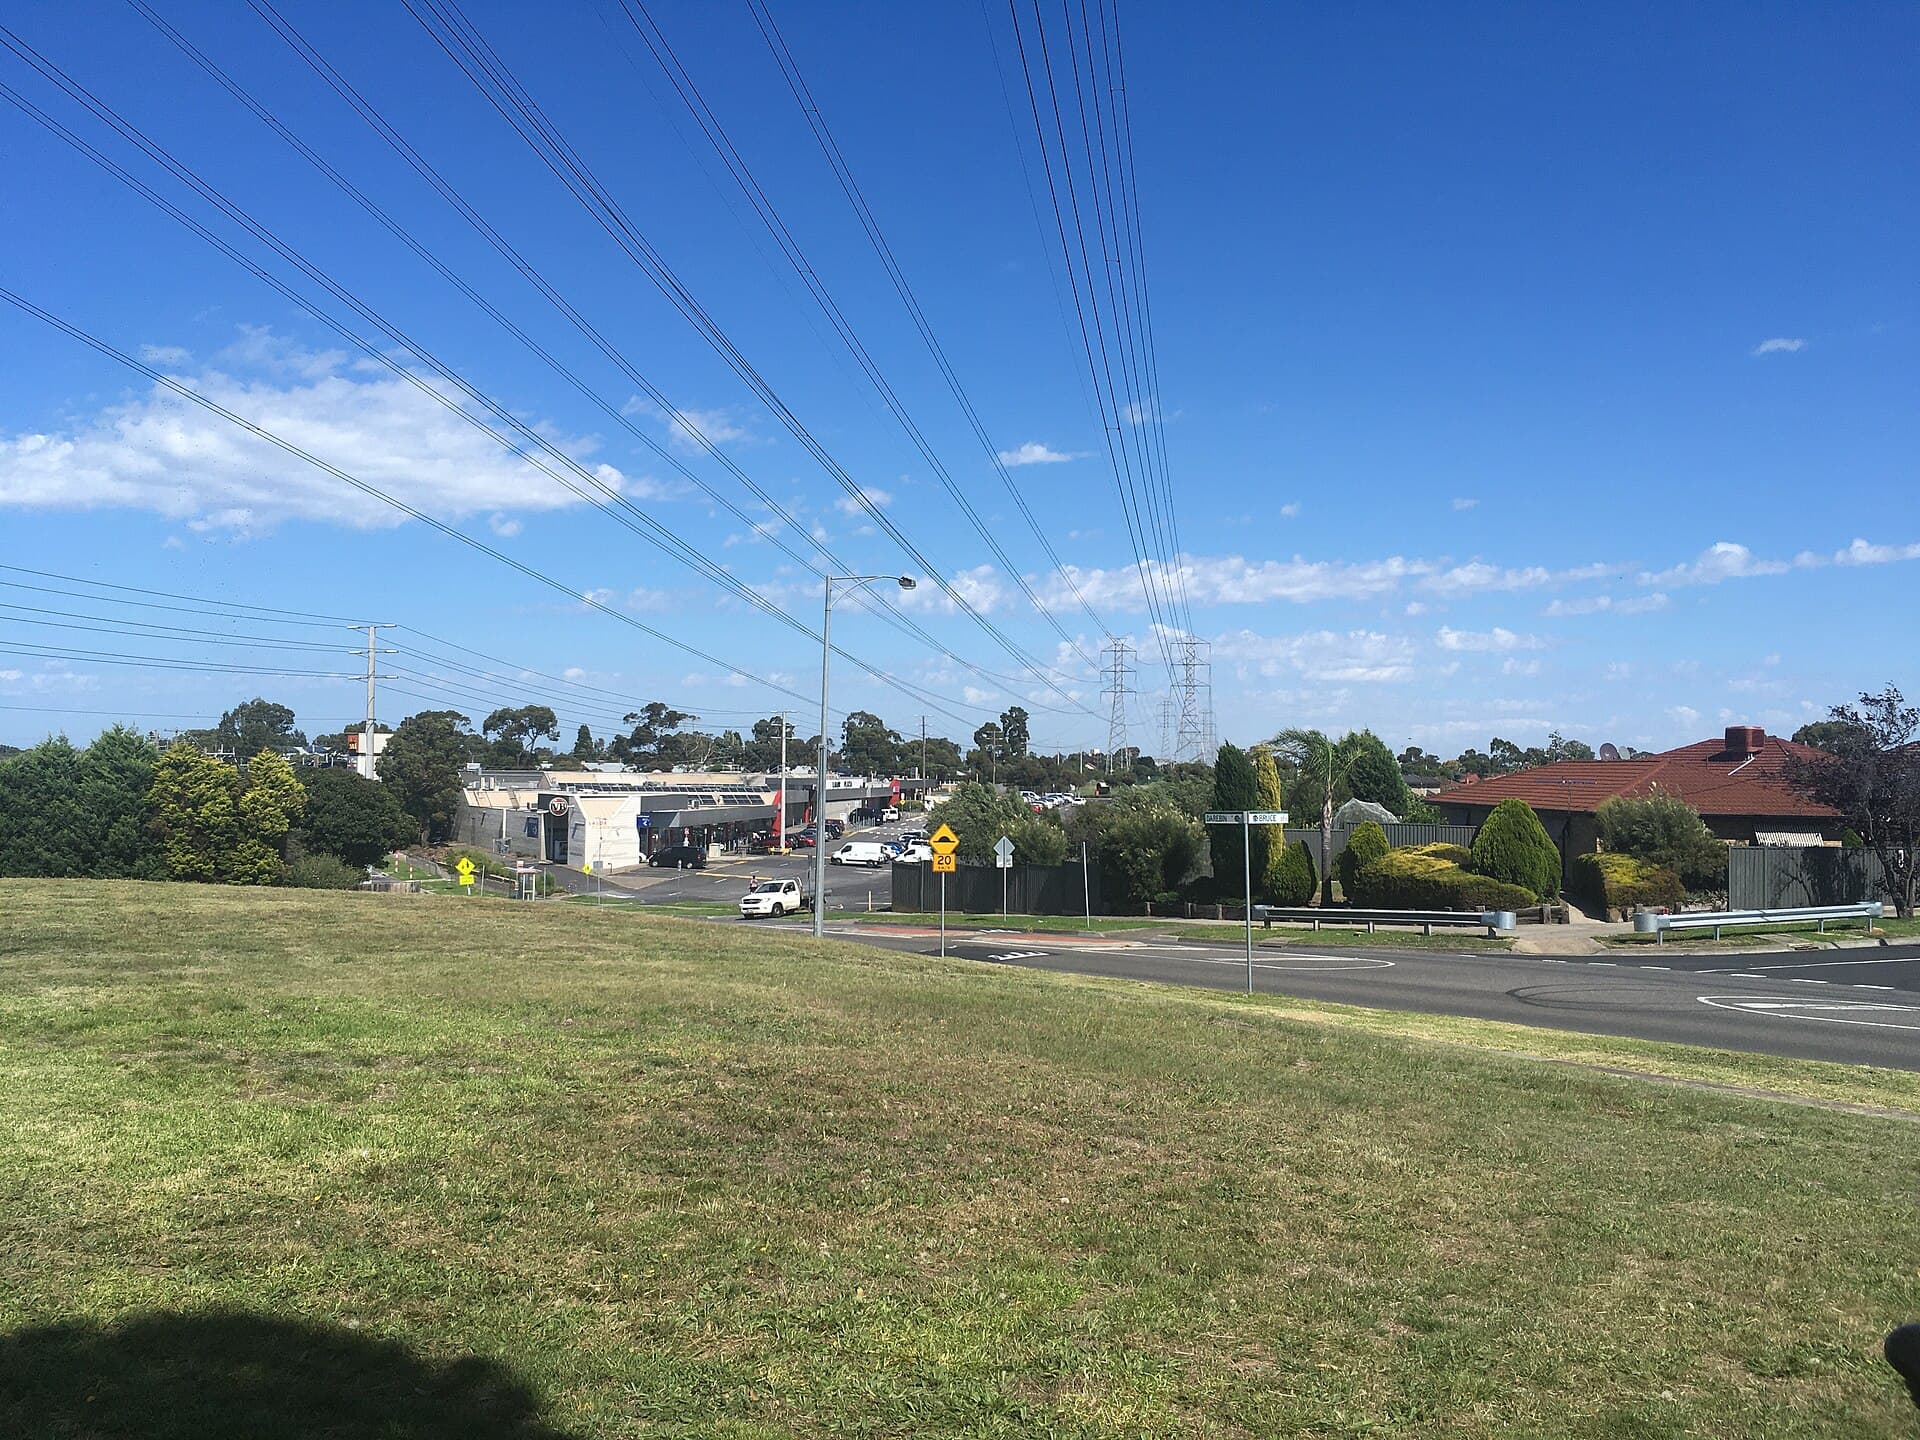
Photo: Philip Mallis. CC BY-SA 2.0. Source. See all image credits.

“Payday loan” is the street name. The legal name, for most of the short-term, small-dollar contracts advertised on late-night radio and in shopping-centre windows, is a small amount credit contract (SACC). The National Consumer Credit Protection Act and the National Credit Code treat these contracts as consumer credit, with special cost caps that do not apply to an ordinary bank personal loan.
That is worth knowing before the website’s green button. A SACC is not “unregulated”. It is regulated differently, and the difference is why a $500 loan can still be an expensive way to get to Friday.
Plenty Credit’s old co-operative in Lalor did not write payday loans. It did write budgeting tips. The two facts still belong in the same paragraph. This guide is general information. It is not a recommendation to take, avoid, or refinance any particular contract.
What is a small amount credit contract?
In outline, a SACC is a consumer credit contract where:
- the amount of credit is $2,000 or less
- the term is between 16 days and 12 months
- the contract is not a continuing credit contract (it is not a credit card)
- the credit provider is not an authorised deposit-taking institution — not a bank, credit union or building society in the usual sense
If the loan is larger, or longer, or structured as a line of credit, other rules apply. Medium amount credit contracts have their own fee and interest settings. Do not assume a $2,100 loan is “just a slightly bigger payday loan”. It may be a different legal animal with a different price cap.
SACCs became a political and regulatory problem because a small principal, a short term, and a fee that is a large percentage of the principal produce a crushing effective cost. Parliament responded with caps, disclosure, and — from June 2023 — a tighter income test. ASIC polices the sector. MoneySmart’s page on payday loans is the government explainer to keep open in another tab.
A lender offering these contracts generally needs an Australian credit licence, membership of AFCA, and a responsible-lending process. The quality of that process is one of the things people complain about. Licensing is not a quality star. It is a minimum.
How much can a payday lender charge?
For SACCs, the familiar caps — and you should still read the actual contract, because this is not legal advice — look like this:
- an establishment fee of up to 20 per cent of the amount of credit
- a monthly fee of up to 4 per cent of the amount of credit, for each month of the term
- no interest in the ordinary personal-loan sense
- limits on default fees, and an overall cap on how much the lender can recover if you fall behind (commonly described as twice the amount of credit, including fees already paid — check the current Code and the contract)
Worked picture, not a quote. Borrow $1,000 for four months. A 20 per cent establishment fee is $200. Monthly fees at 4 per cent could be $40 a month. You can see how a short loan becomes a several-hundred-dollar exercise without anyone writing “interest rate: 200 per cent” on the shopfront.
There are also rules about what the lender must consider before it says yes, including recent bank statements. Reforms that commenced in June 2023 tightened that assessment and the proportion of income that SACC repayments may consume. Unsolicited offers of this kind of credit have also been a target of the reforms. If a text message offers you a pre-approved payday loan you did not ask for, treat it as a warning label, not as luck.
Fees outside the cap are the next place to look. Direct-debit dishonour fees, “optional” services, and related products have historically been where some operators tested the fence. If the total you must pay does not match the establishment-plus-monthly arithmetic, ask the lender to explain every line in writing before you sign.
What is the 10 per cent income test from June 2023?
From 12 June 2023, a protected earnings amount applies to SACCs in a stricter form than the older Centrelink-focused rule. In everyday language, the total repayments on your small amount credit contracts are generally not supposed to exceed 10 per cent of your net income.
That is a cap on the slice of income the SACC channel may take, not a finding that 10 per cent is comfortable. Ten per cent of a low income is still rent-adjacent money. The test exists because people were stacking several short-term loans until the debit ran every payday.
Practical consequences:
- the lender should be looking at your income and at existing SACC repayments, not only at the loan you are applying for today
- bank statements (commonly around 90 days) are part of how that is checked
- a second or third SACC is harder to justify if the 10 per cent is already spoken for
- the older idea that “Centrelink customers had a special percentage, and everyone else was free range” is not the current design. The 10 per cent frame is broader
This is still not a substitute for responsible lending more generally. Unsuitability is a wider question than one percentage. If a lender approved a SACC that was always going to bounce, that can be material later at AFCA.
If your income is Centrelink, casual, or mixed, say so plainly on the application. “Tidying” the statements so the loan looks fine is how people end up with a contract they cannot perform and a file they cannot explain.
Why do comparison rates on payday loans look huge?
Because they are doing the job comparison rates were invented for: showing the cost of fees on a short term, expressed as a yearly figure.
A 20 per cent fee on a one-month loan is not a 20 per cent annual percentage rate. Once you annualise it, the comparison rate can print as several hundred per cent. Shoppers see that number and assume the website is broken. It is not. The product is expensive, and the term is short.
Use the comparison rate to compare two SACCs with similar amounts and terms. Do not use it to compare a four-week SACC with a three-year credit-union personal loan as if they were the same animal. Also look at dollars: how much you will pay in total, on which dates, and what happens if a debit fails.
MoneySmart’s payday loan guidance walks through this without a sales overlay. If a lender hides the comparison rate, or shows only “from $15 a week” without the term and the total, you do not have a complete offer.
Can you get a payday loan if you receive Centrelink?
Sometimes. The law does not say “no Centrelink, no loan”. It does say the lender must assess unsuitability, and the protected earnings amount now limits SACC repayments as a share of net income — including, for many households, income support.
Issues that come up repeatedly:
- Timing. Debits that land the day before a payment can empty the account that was supposed to cover food.
- Multiple deductions. Rent, electricity, child support and an existing SACC may already be sitting on the same payment.
- The 10 per cent test. Existing SACC repayments count. A new loan on top can push the file over the line even if each loan looks small.
- Evidence. Lenders should be reading statements, not only a tick-box that says “employed”.
If the reason you want a SACC is that a Centrelink payment did not stretch, a short-term loan with a 20 per cent establishment fee is a steep way to borrow from next fortnight. A free financial counsellor via the National Debt Helpline on 1800 007 007 will not be offended if you say that out loud. They have heard it. How to budget when you have debt is the household version of the same conversation.
Hardship still exists on a SACC. If you cannot pay, tell the lender in writing. See financial hardship: how to ask your lender for help. Do it before the default fees and the collection notices write the next chapter.
What happens if you cannot repay a SACC?
The sequence is drearily familiar: failed debit, fees, contact, collections, and the possibility of a default listing on a credit file. The SACC cost caps include limits on what can be recovered in default, but “capped” is not “free”. A listed default can sit on a file for years and make ordinary credit harder. What happens if you default on a loan covers that path for credit contracts generally.
Do not take a second payday loan to pay the first. Stacking is how the 10 per cent test was born. Do not use a credit card cash advance to look as if the SACC is paid if the card is already in trouble. You have only moved the fee.
If the lender’s conduct is the problem — approval that ignored the statements, harassment, fees that do not match the cap, a refusal to consider hardship — use the lender’s internal dispute process, then AFCA. AFCA is free for the individual. ASIC also takes reports about licensed credit providers, though it is not your private advocate in a single loan dispute.
Credit-repair companies that promise to erase a genuine SACC default because “payday loans are illegal” are overreaching. Many SACCs are legal. The question is whether this contract and this lender complied. That is a documents job, not a Facebook-ad job.
Are there cheaper alternatives?
Often, yes — which is not the same as “easy”.
Alternatives people actually use, depending on the situation:
- a hardship variation on an existing loan or card, which does not require a new high-cost contract
- a payment plan with the biller you are actually trying to pay (energy, telco, council, the dentist)
- a small loan from a bank, credit union or community finance provider that is not a SACC, if you fit and if the comparison rate is genuinely better
- family, only if it will not wreck the relationship — and only with the amount and repayment written down
- waiting, if the need is a want that can move a fortnight
No-interest loan schemes and community providers exist in some areas for essential goods. They have eligibility rules and waiting lists. They are not payday shops with better lighting.
If you already have several SACCs, the priority is usually to stop adding more, map the debits, and talk to a counsellor before the next establishment fee. Pull free credit reports so you can see how many enquiries the last month produced. A cluster of payday applications is a red light to every later lender.
The former Plenty Community Credit Union used to occupy a small, local idea of credit: members, a BSB, a conversation about whether the repayment fitted. SACC advertising occupies the opposite idea: speed, privacy, and a fee that is easy to underestimate because it is not called interest. Speed is the feature. The 20 per cent, the 4 per cent, the 10 per cent income test and the comparison rate are the price. Read them in that order, on paper, before anyone’s app logs a debit against Lalor Plaza’s next shop.
For the wider cluster — hardship, defaults, complaints — start at the debt and hardship topic hub rather than at another “instant approval” tab.
Frequently asked questions
What is the maximum a payday lender can charge in Australia?
For a small amount credit contract the usual caps are a 20 per cent establishment fee and a 4 per cent monthly fee on the amount of credit, with a separate cap on how much can be recovered if you default. They are not allowed to charge interest in the ordinary sense. Always check the contract in front of you.
Can I get a payday loan if I receive Centrelink?
Receiving Centrelink does not automatically ban a SACC, but the protected earnings amount and the lender’s responsible-lending assessment still apply. From June 2023, total SACC repayments are generally limited to 10 per cent of net income for consumers, not only for people on income support.
Why is the comparison rate on a payday loan so high?
Because a large fee is being applied to a small amount over a short term. Annualising a 20 per cent establishment fee plus monthly fees produces a comparison rate that can run into hundreds of per cent. That is the product, not a display error.
Questions about this guide? Contact the Plenty Credit desk or read our editorial standards.
More in Debt and hardship
How to complain to AFCA about a credit provider
AFCA is the free external dispute body for most licensed lenders, card issuers and BNPL providers. You usually complain to the firm first, then lodge online with documents and dates. This is general information, not legal advice.
9 min read · 12 July 2026
What happens if you default on a loan in Australia
A missed payment is not automatically a default listing. Here is the usual path from a late repayment through collections, credit-file listings, court, and why hardship and AFCA can still matter. General information, not advice.
9 min read · 30 May 2026
Debt consolidation loans in Australia: when they help and the risks
Rolling several debts into one loan can lower the monthly figure and raise the total interest. Here is how consolidation actually works, including secured loans against a car or house, without treating it as advice.
9 min read · 8 March 2026