How to apply for a personal loan in Australia
A personal loan application is a responsible-lending assessment, not a formality. Here is the paperwork Australian lenders usually want, why the quote is not the billboard rate, and how a credit score enters the decision.
Published 11 March 2026 · Updated 16 October 2026 · 9 min read
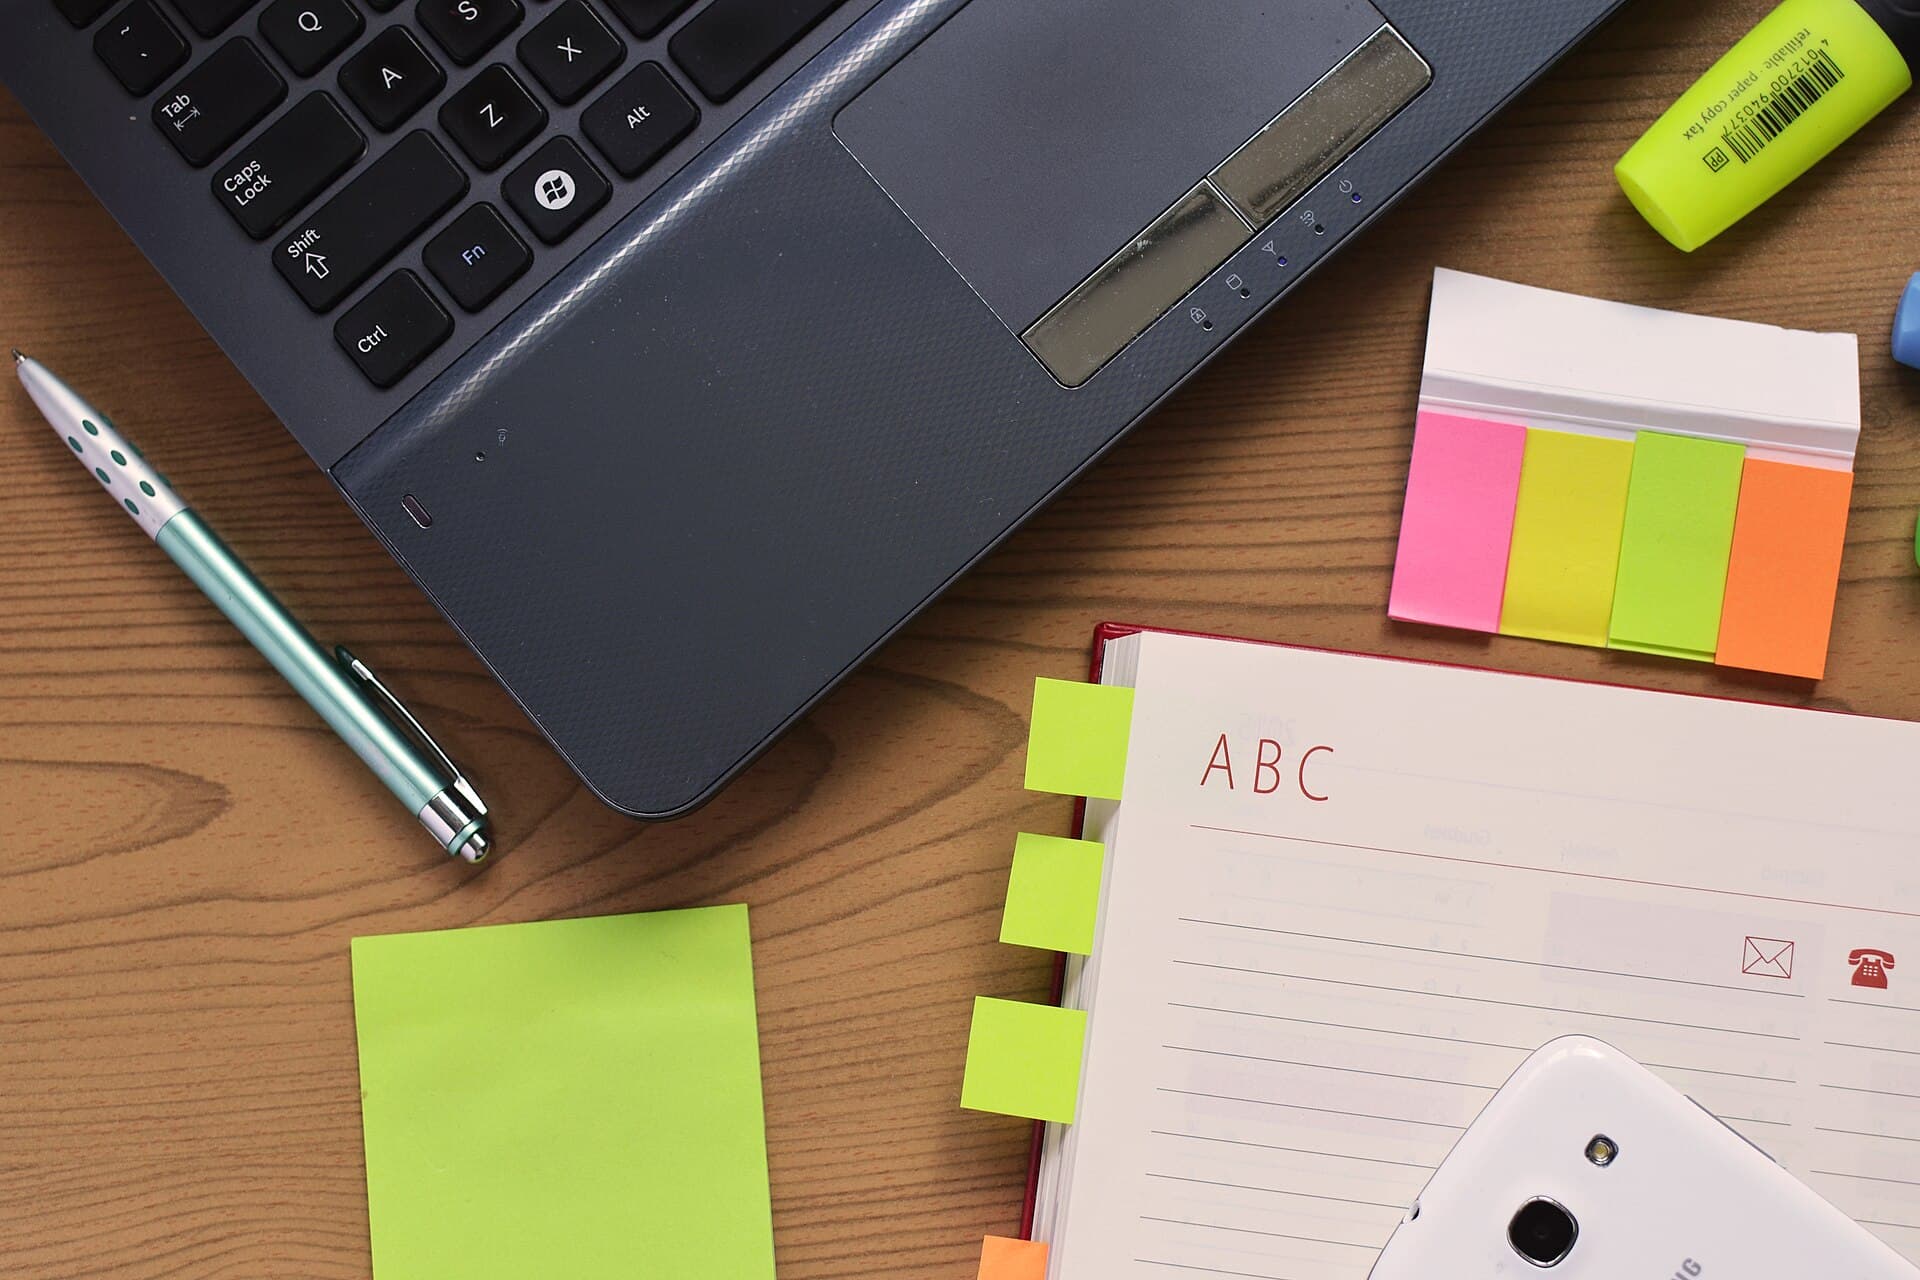
Photo: www.Pixel.la Free Stock Photos. CC0. Source. See all image credits.

Applying for a personal loan in Australia is less like clicking “buy now” and more like sitting at a kitchen table with a laptop, a notebook and a pile of PDFs. The lender is not only deciding whether they like you. Under the National Consumer Credit Protection Act they are deciding whether the contract would be unsuitable — whether you could comply, and whether you could do so without substantial hardship.
The old Plenty Credit Co-operative application was a paper pack. The questions have moved online. They have not become decorative. This guide walks through the documents, the assessment, the waiting, and the gap between an advertised rate and the number on an offer. It is general information, not a suggestion that you should apply.
ASIC’s personal loans page and the National Credit Code are the public references. The responsible-lending duties sit in the National Consumer Credit Protection Act 2009, which we unpack in what responsible lending means for borrowers.
What documents do you need to apply for a personal loan in Australia?
Lenders differ, but the pile is recognisable. Have it assembled before you start the clock on an enquiry.
Identity. An Australian driver’s licence or passport is the usual first document. Some lenders also want a Medicare card or a utilities bill that matches the address on the application. A mismatch — a licence in Reservoir, a bill in Lalor, an application typed with a third spelling of a middle name — is how automated checks stall.
Income. Recent payslips (often the last two), a year-to-date figure, and sometimes a group certificate or income statement from myGov. If you are paid extra as overtime, commission or penalty rates, lenders may treat only a portion as ongoing. Casual and contract workers are often asked for a longer history.
Self-employed applicants typically need tax returns, notices of assessment, and sometimes Business Activity Statements. “I turn over plenty” is not a document.
Other income. Family tax benefit, rent from a spare room, shared household contributions. If you want it counted, bring evidence. If you do not, do not invent it. False information on a credit application is not a paperwork shortcut.
Expenses. This is the section people under-prepare. Rent or board, groceries, transport, insurance, school costs, medical, subscriptions, and the unglamorous rest. Some lenders pre-fill an industry benchmark and ask you to confirm. Confirming a number that is lower than your real life is how a loan that looked fine on Tuesday becomes a hardship letter in August.
Existing debts. Every credit card limit (not only the balance), every personal loan, car loan, buy now pay later account, and any HECS-HELP repayment that already comes out of the payslip. Limits matter because responsible lending looks at what you could be asked to pay, not only what you paid last month.
The purpose. Many applications ask what the money is for. “Debt consolidation”, “car”, “renovations”, “other” are not moral categories, but they change the follow-up documents — a quote from a dealer, a payout figure from another lender, a council invoice. A vague purpose plus a round number is a classic delay.
If the loan will be secured, add proof of the asset: registration papers, a valuation or invoice, insurance, and for a used car a PPSR conversation that belongs in the car-loan checklist.
What is responsible lending and why does the lender ask about expenses?
Australian credit licensees generally must not enter a consumer credit contract that is unsuitable for the consumer. The assessment looks at whether you could comply with the contract and whether you could do so without substantial hardship, and whether the contract meets your requirements and objectives. The statute is dry. The effect on an application is not: the lender is expected to ask, and in many cases to take reasonable steps to verify.
That is why a lender may:
- request bank statements, not only a payslip
- telephone you about a regular gambling debit or a BNPL cluster
- refuse to count a board payment from a relative that cannot be shown
- decline an application even when a comparison site said you were “pre-approved”
“Pre-approved” on an advertisement is a marketing phrase. It is not the statutory assessment.
If the conversation feels nosy, that is the design. The former credit union on May Road asked similar questions across a desk because a loan that does not fit becomes a collections file, and collections files used to sit in the same building as the people who wrote the loan. Online lenders are more distant. The duty is still there.
Expenses are also where people accidentally talk themselves into a larger loan than the budget supports. If the repayment only works when groceries are fictional, the kind answer is a smaller amount or no loan, not a longer term. Comparing personal loans before you apply is how you avoid discovering that in the assessment.
How long does a personal loan application take?
There are at least three clocks, and websites like to quote the shortest.
The automated decision. Minutes, sometimes seconds. This is a first filter: identity, bureau score, stated income versus stated debts. A “yes” here is often conditional.
Verification. Hours to several business days. A person or a second system reads the payslips, statements and, if relevant, the security documents. This is where overtime is shaved back and a forgotten card limit appears.
Offer, cooling-off habits, and funding. Even after an approval, you should still read the credit contract before you accept. Funding to your account, or to a car dealer, can be same-day or can wait on a disbursement authority.
If you apply on a Friday night, do not treat Saturday silence as a decline. If you apply with a term deposit as security, or as a newly arrived resident, expect the long clock. Speed is a feature lenders advertise. Completeness is the feature that actually moves money.
Keep copies of everything you upload. Portals expire. The notebook next to the laptop is not nostalgia.
Why is the quoted rate different from the advertised rate?
Because the advertised rate is commonly a “from” rate for a borrower in a preferred band. The quote is a risk price for you, on this amount, this term, this security, this week.
Reasons a quote moves — none of them a personal diagnosis:
- The comparison-site tile assumed a secured loan and you applied unsecured, or the reverse.
- The advertised comparison rate used an example amount and term that are not yours. See what a comparison rate includes.
- Your bureau file is thinner, younger, or more enquired-upon than the model behind the billboard.
- Existing card limits, not balances, pushed the serviceability maths.
- The purpose or employment type sits outside the campaign the rate was printed for.
A quote that is worse than the ad is still a quote. You can decline it. You can ask whether another product in the same group — a shorter term, a smaller amount, a secured variant — is priced differently. You should not accept a number you do not understand in order to keep a “conditional approval” alive.
If several quotes are wildly different, the applications may not be for the same product. Line them up as you would in a comparison: amount, term, fees, security, early-repayment rules. Then decide whether a second application is worth another enquiry.
Does applying for a personal loan affect your credit score?
Usually, yes, in the small, factual way: the lender makes an enquiry on a credit reporting body. That enquiry is visible to later lenders. A single enquiry is ordinary. A row of them in a fortnight is a story, and not a flattering one.
Before you apply:
- Get the free files from Equifax and Experian. How to get a free credit report is the method. You cannot usefully guess what the lender will see.
- If the file is messy, spend the next period on improving the score — on-time payments, fewer fresh applications — rather than on a hope that this loan will “build credit”.
- Ask whether a rate estimate is a soft look. Hard versus soft enquiries is the distinction. Do not take a button labelled “check my rate” at its word; take the lender’s written description.
Checking your own report does not work like an application. Applying five times after you have checked it does.
MoneySmart’s pages on credit scores and credit reports are the regulator’s plain-English version of the same warning.
What happens after you accept an offer?
You receive a credit contract and, if relevant, security documents. Read them. The interesting pages are still the fee schedule, the default clauses, the early-repayment rules and any direct-debit authority. Acceptance is how a quote becomes a regulated contract under the National Credit Code.
Funding may go to you or to a third party. If it is a consolidation, confirm the old accounts are actually paid out and closed; leftover open cards with empty balances still show as limits. If it is a car, confirm the PPSR registration matches the contract you signed.
Set the repayment to leave the account the day after you are paid, not the due date minus optimism. If, after funding, the repayment will not fit, hardship is a right to ask, not a right to a particular outcome. Financial hardship help is the next guide, and it is better read early.
What if you are declined?
A decline is information. Ask, politely and in writing, whether the lender will say why — serviceability, credit file, employment, purpose, security. They may give a general reason. They may not give a score.
Then:
- Pull the files again if you have been refused credit; that is a separate ground for a free copy.
- Correct errors. Do not hire a credit-repair advertisement to write the letter you can write.
- Wait before you fire the same application at four more logos. The enquiries will stack.
- If you already cannot meet existing repayments, a new application is the wrong tool.
The desk, the laptop and the pen are still the right picture. An application that is prepared slowly is cheaper than an application that is repeated quickly. Plenty Valley households used to bring a folder to the branch. The folder still works. The branch is optional.
Frequently asked questions
What documents do I need to apply for a personal loan in Australia?
Expect photo identification, recent payslips or tax returns, evidence of other income, a picture of living expenses, and a list of existing debts and their repayments. Self-employed applicants are usually asked for more than two payslips.
How long does a personal loan application take?
An online decision can arrive in minutes and still be conditional. Unconditional approval, document checks and settlement more often take days. Complex income or a security asset can stretch that to a week or more.
Does applying for a personal loan affect my credit score?
A formal application typically produces a hard enquiry on the bureau the lender uses. One enquiry is a data point. Several in a short window read as stress. Checking your own report is not the same thing.
Questions about this guide? Contact the Plenty Credit desk or read our editorial standards.
More in Personal loans
Personal loans vs credit cards vs buy now pay later
Three ways to pay later, three different clocks. Personal loans, credit cards and buy now pay later do not cost the same, last the same, or look the same on an Australian credit file — and stacking them is how a small gap becomes a file.
9 min read · 30 June 2026
Car loans in Australia: what to check before you sign
The weekly figure on the windscreen is not the cost of the car. Dealer finance, balloon payments, insurance add-ons, used-car history and the PPSR all change what you drive away owing.
9 min read · 27 May 2026
What is a comparison rate and why it matters
A comparison rate is a legal percentage, not a marketing badge. It folds most known fees into a single figure — but the $150,000 over 25 years example on many ads is the wrong picture for a personal loan.
9 min read · 19 April 2026