Does buy now pay later affect your credit score?
BNPL can now show up as enquiries, accounts and missed-payment history, especially after the 2025 low cost credit rules. Multiple accounts, stacking, and paying BNPL with a credit card all change the picture. General information only.
Published 2 August 2026 · Updated 18 October 2026 · 9 min read
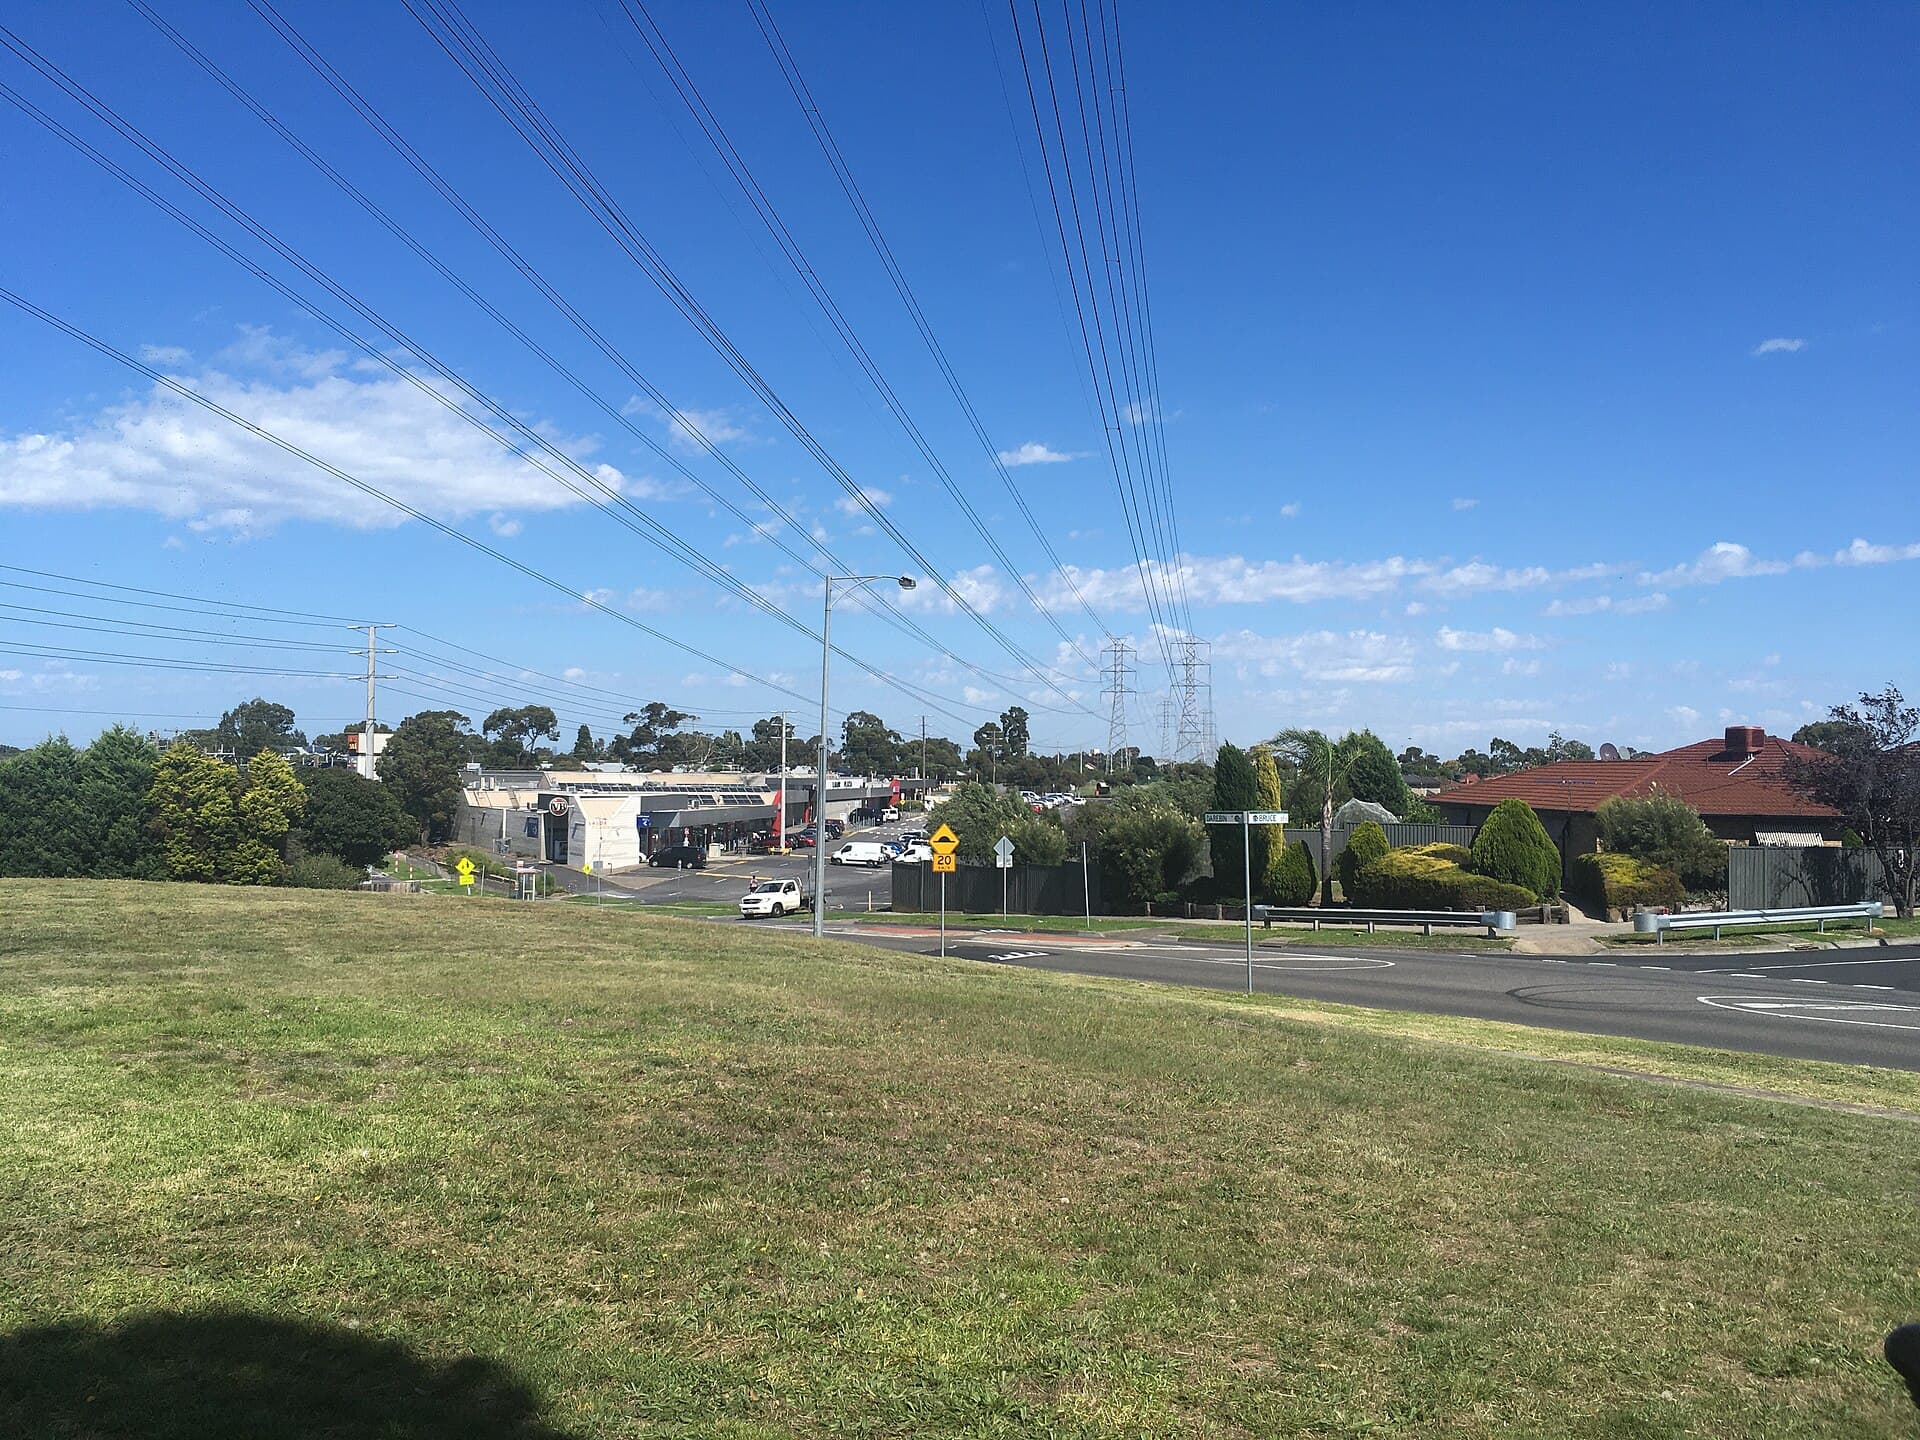
Photo: Philip Mallis. CC BY-SA 2.0. Source. See all image credits.

The honest answer used to be “it depends, and often not in the way a card does”. That answer is now too small. From 10 June 2025, many buy now pay later products are low cost credit contracts under the National Credit Act. Providers who report to Equifax or Experian can place the account, the enquiry, and the repayment history on the same kind of file a lender reads for a personal loan.
Whether your score moved last month is still a facts question. Different apps, different bureaus, different limits. Plenty Credit cannot see your file. You can. How to get a free credit report in Australia is the first practical step, before any theory.
This is general information, not a suggestion to open, close or freeze a BNPL account. The old Plenty Community Credit Union in Lalor would have said the same in plainer furniture: look at the statement, then look at the file.
Does applying for BNPL create a credit enquiry?
It can. An enquiry is a record that a credit provider looked at your file in connection with an application. Lenders read a cluster of enquiries as appetite for credit, or as stress. Five BNPL applications in a fortnight can look like five small versions of the same problem.
Not every BNPL sign-up produces a hard enquiry. Some providers use an internal score, a bank-statement feed, or a milder bureau product. Some used to advertise “no credit check” in the years when the product sat outside the National Credit Code. Treat leftover slogans with suspicion. The 2025 BNPL rules sit on modified responsible lending (ASIC’s RG 281 themes). An assessment can involve a bureau look even if the app’s marketing is still written like 2019.
After you apply:
- Note the date and the provider’s legal name.
- Wait for the file to update — not always overnight.
- Open the enquiries section on both Equifax and Experian.
- See whether the look is there, and how it is labelled.
If you are rebuilding a score, adding a new BNPL enquiry to shop for headphones is usually the opposite of the plan in how to improve your credit score. If you already have the account, a later limit-increase request can produce another look. Ask the provider, in the app’s legal screens, what it will do before you tap.
A “soft” look that does not show to other lenders is not a moral victory if you still cannot pay the instalments. The enquiry is the smaller of the two issues.
Do missed BNPL payments affect your credit score?
They can, and they can do it in more than one field.
Repayment history information is the monthly picture: on time, 1–29 days late, and so on. Once a BNPL account is reported like other consumer credit, a missed instalment can leave a late mark. Those marks typically remain visible for a shorter period than a default (commonly two years). They still move a score, especially if they repeat.
A default listing is heavier. It is not a single failed debit. It is a listed overdue amount that met the credit-reporting rules — generally including an overdue period and a notice. Default information is commonly visible for five years from listing. Paying later should update the status to paid; it does not usually rewind the date. What happens if you default on a loan explains the difference between a late payment, a default notice under the National Credit Code, and a listing.
Before 2025, many people missed a BNPL debit, paid a late fee, and heard nothing more. Some still will, if the provider does not report, or if the amount is tiny and the process is not worth the provider’s while. Do not budget as if silence were a right. Licensed LCCCs sit closer to ordinary credit conduct, including hardship and enforcement pathways.
If you can see a miss coming, write to the provider and ask for hardship before the debit fails. A variation is cheaper theatre than a listing. The National Debt Helpline on 1800 007 007 can help you sequence several BNPL accounts against rent.
MoneySmart’s pages on credit scores and credit reports and buy now pay later are the official pair to read with this one.
Does having multiple BNPL accounts hurt your score?
Multiple accounts can hurt in three mechanical ways, even if every instalment is currently on time.
Enquiries. Each application can add a look. A wallet with Afterpay, Zip, a shop-branded plan and a newer app can be four enquiries before anyone is late.
Available credit and utilisation. If BNPL limits are treated like revolving credit, unused limit can look like room to spend. Used limit can look like load. Scoring models are not identical, and BNPL is still being digested by them. The conservative household reading is: four open BNPL limits are four open appetites. Lenders who still think in cards will add them up with the cards.
Conduct risk. Several small instalments are easy to lose in a calendar. One missed debit on account A and an on-time tick on account B is still a late mark. People do not miss BNPL because they are careless about $30. They miss it because four $30 debits, a phone plan and rent share a Tuesday.
There is no prize for holding every brand. Closing an account you do not use can reduce temptation and, depending on how it is reported, tidy the file. Close it in the app and confirm in writing if the provider offers email. Then check the report a cycle later so “closed” means closed.
If the reason you have several accounts is that each one was a declined-limit workaround, that is stacking by another name. Stop opening new ones and map the debits. How to budget when you have debt is more useful here than a new app.
What happens if you pay BNPL with a credit card?
You have not prepaid. You have moved the instalment onto revolving credit.
If the card is paid in full during the interest-free period, the extra damage may be small: a tap, a bit more utilisation for a few weeks, perhaps a reward point the marketing department is proud of. If the card carries a balance, you can pay interest on a purchase the BNPL ad described as interest-free. That is not a score trick. It is an expensive loop.
Score effects to watch:
- card utilisation goes up when the BNPL debit hits the card
- a missed card payment is a mainstream repayment-history event, even if the BNPL provider was paid
- the BNPL account may look clean on the bureau while the card looks worse — lenders who read the whole file will not be fooled
- some cards treat BNPL as cash-like or as a purchase; the contract decides whether the interest-free period applies. Read it.
Paying BNPL from a transaction account you actually have money in is the dull method. If that account is empty, the problem is the budget, not the funding source. A payday loan to clear a BNPL debit is a step into a higher-cost product to protect a lower-cost one. That is usually the wrong direction.
What is BNPL stacking?
Stacking is holding several BNPL arrangements — or a BNPL plus a card plus a SACC — so that the combined instalments only fit on a good week. Each provider may have seen only its own limit. Modified responsible lending is supposed to reduce that blindness. It will not reduce it to zero. People can still open accounts close together, use different email addresses, or spend to the cap on every app before any debit has bounced.
Stacking shows up on a file as:
- several recent BNPL enquiries
- several open BNPL accounts
- rising card balances if the card is the backup
- then, if it fails, a cluster of late marks rather than one
From a lender’s chair, stacking is not clever. It is the same pattern as maxing two store cards in 1998, with a nicer interface. From a household chair in Lalor Plaza, it is how a quiet month of clothing and takeaway becomes a noisy month of debits.
If you already stacked, do not open another product to “consolidate” BNPL unless you have run the total-repayable test in debt consolidation loans. Many consolidation loans are longer and more expensive than simply freezing the apps and paying them down. Hardship on each BNPL account is the Code-shaped option if they will not fit.
ASIC did not invent stacking as a moral failing. It regulated BNPL because stacking was common and the old law did not see it. RG 281 and the LCCC rules are the response. Your response is a list of every instalment date on one page.
How do the 2025 rules change credit reporting?
They make reporting more likely, more standardised, and more consequential.
Licensed low cost credit providers sit inside the same broad credit-reporting world as other credit providers. They can contribute comprehensive credit reporting data. They can list defaults if they follow the notice rules. They must handle hardship. They must belong to AFCA. A dispute about a listing is no longer an argument with a start-up’s helpdesk that “isn’t regulated”. It is IDR, then AFCA, with ASIC in the background.
What may appear on a file after 10 June 2025, depending on the provider:
- the BNPL account as an open (or closed) credit account
- the credit limit or the typical limit
- repayment history
- default information
- enquiries
What still may not appear: every merchant-level purchase. A credit report is not a shopping receipt. It is a file about credit. The shoes are your business. The missed third instalment can become the bureau’s business.
If a listing is wrong — not your account, already paid, listed without the required notice — dispute it. If it is right, credit-repair companies cannot lawfully magic the date away. ASIC has said so, repeatedly.
On-time BNPL can, in theory, add a thin stream of positive repayment history for people who have little other credit. That is not a reason to open BNPL “to build a score”. Plenty of thin-file Australians have tried that with store cards and discovered they had built a utilisation problem instead. If you want a score strategy, start with the reports and the on-time debts you already have.
What should you check on your credit report?
A BNPL-specific pass, once you have the PDFs:
- Identity. Make sure the BNPL account is actually yours.
- Enquiries. Match them to applications you remember. A look you did not make is a red flag.
- Open accounts. Closed apps should say closed. An old limit still showing as open is still a limit in someone else’s model.
- Repayment history. One late mark is not a default. A row of them is a pattern.
- Defaults. Check dates, amounts, and whether paid.
- Duplicates. Some people find the same BNPL on both bureaus with different arrears. That is a dispute letter, not a shrug.
Then leave the PDFs in a folder dated today. Scores on phone apps are summaries. The missed instalment is the fact. Responsible lending is what the provider was supposed to do at the start. Hardship is what you do if the instalments will not fit now. AFCA is what you do if the provider mishandles either.
Lalor Plaza from Casey Drive Park is an ordinary view: cars, a shopping centre, a suburban afternoon. BNPL was built for that afternoon. The credit file was built for the morning after, when a lender in Collins Street asks whether those afternoons still fit. Pull the file, count the apps, and treat instalments as credit — because, as of 2025, in the cases the law now covers, they are. More on the product sits in the buy now, pay later hub; more on the file sits under how to improve your credit score.
Frequently asked questions
Does applying for buy now pay later hurt your credit score?
It can, if the provider makes a credit enquiry that the bureau treats like other applications. Some checks are milder. The only reliable method is to read the provider’s disclosure and then look at your Equifax and Experian files after you apply.
Do missed BNPL payments appear on a credit report?
They can, particularly once the account is a regulated low cost credit contract that the provider reports. A late instalment may show in repayment history. A serious overdue amount may be listed as a default if the listing rules are met.
Is paying BNPL with a credit card bad for your score?
The BNPL may show as paid while the card balance and utilisation rise. If the card is then paid late, the score problem is the card. You have not hidden the spending. You have moved it onto revolving credit.
Questions about this guide? Contact the Plenty Credit desk or read our editorial standards.
More in Buy now, pay later
Buy now pay later in Australia: how the new rules work
From 10 June 2025 many BNPL products are regulated as low cost credit contracts under the National Credit Act, with modified responsible lending, hardship, AFCA and credit reporting. General information, not legal advice.
9 min read · 12 June 2026