Debt consolidation loans in Australia: when they help and the risks
Rolling several debts into one loan can lower the monthly figure and raise the total interest. Here is how consolidation actually works, including secured loans against a car or house, without treating it as advice.
Published 8 March 2026 · Updated 18 October 2026 · 9 min read
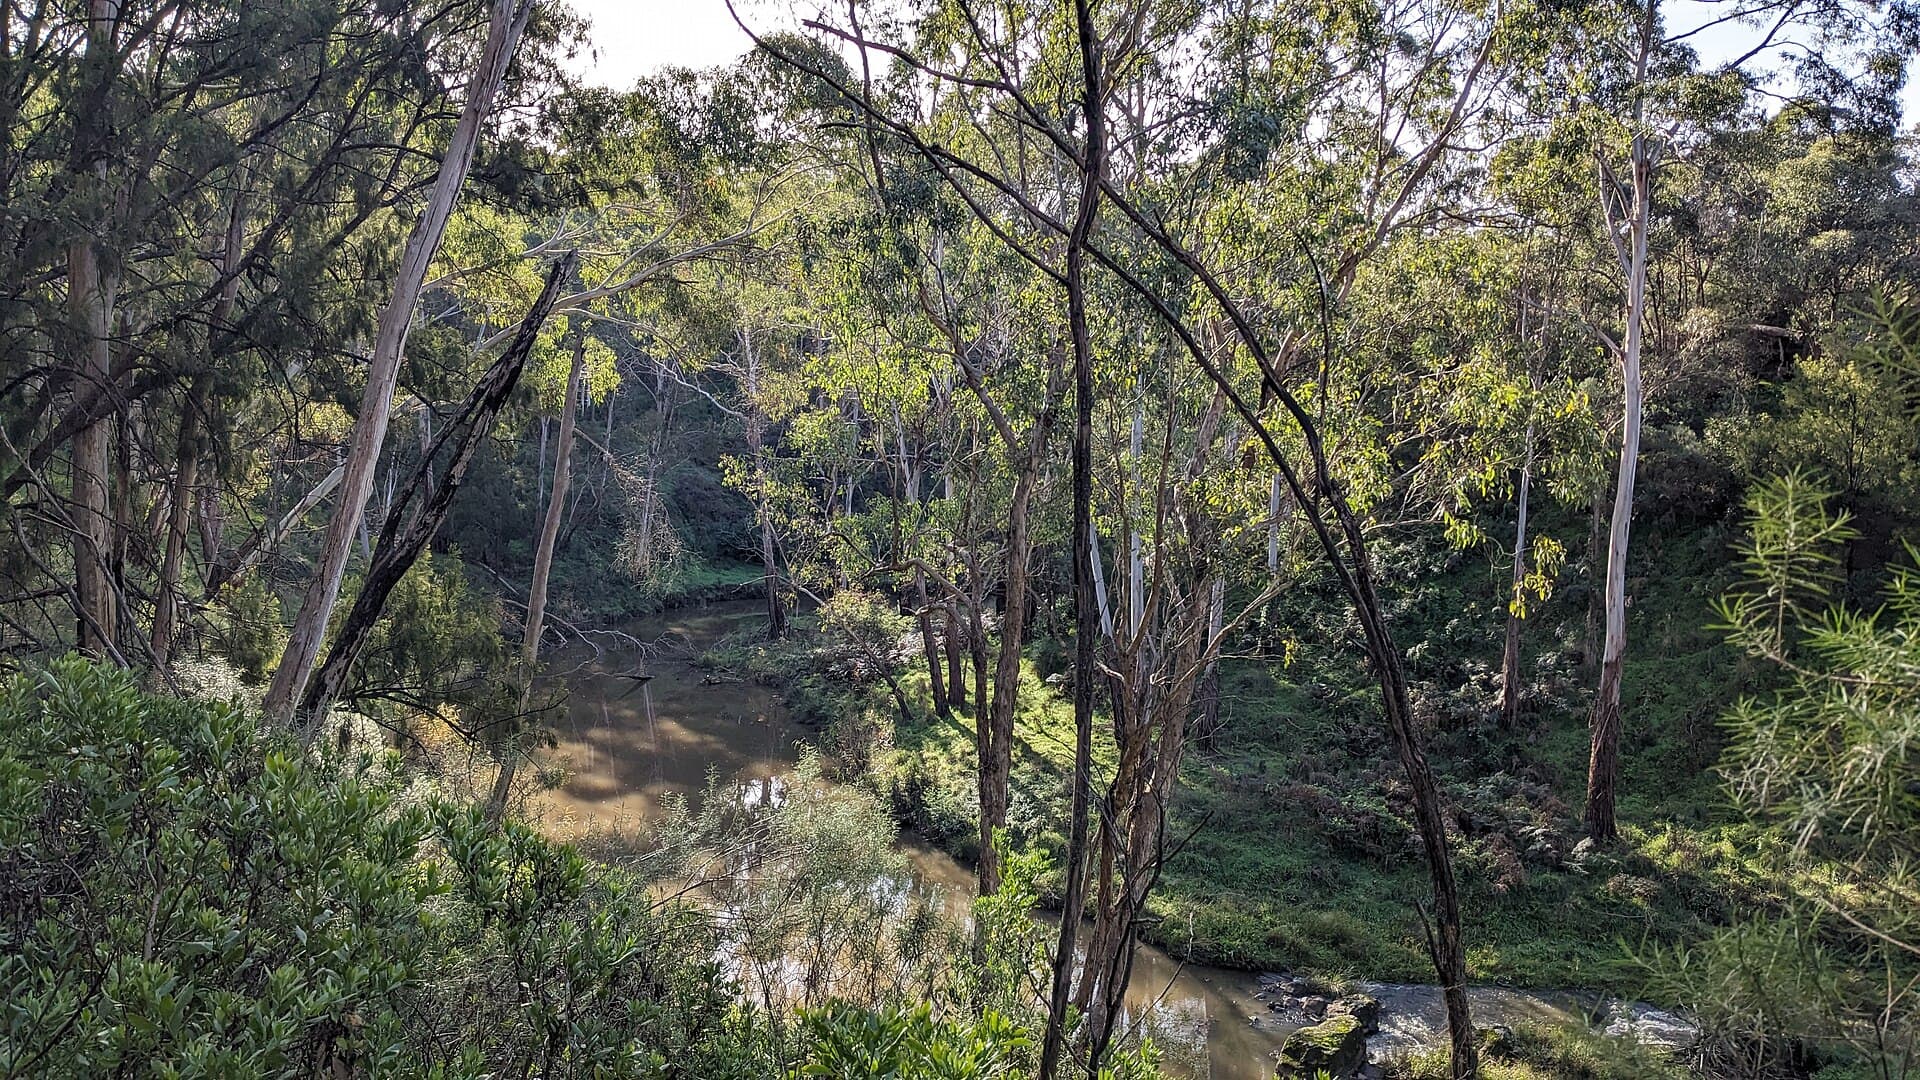
Photo: Philip Mallis. CC BY-SA 2.0. Source. See all image credits.

Debt consolidation is sold as tidiness. One repayment. One due date. A number that looks smaller than the sum of the old minimums. Sometimes that is what happens. Sometimes the smaller number is just the same interest stretched over more years, with a new establishment fee and a new enquiry on the file.
Plenty Credit writes about this the way the old Plenty Credit Co-operative used to talk about personal loans in the Plenty Valley: slowly, with the contract on the table. Consolidation is a product, not a personality upgrade. It can help when the arithmetic is honest. It can also turn unsecured card balances into a loan secured by the car in the driveway, or by the house.
This is general information, not a suggestion that you apply for a loan, close a card, or put a mortgage in harm’s way.
What is a debt consolidation loan?
A consolidation loan is a new credit contract used to pay out two or more existing debts. Typical ingredients are credit cards, store cards, personal loans, car finance, overdue BNPL, and sometimes a tax or utility bill that a lender is willing to include.
After settlement, you are supposed to owe the new lender and not the old ones. That only happens if the payout figures are current, the funds actually go to those accounts, and you do not treat the emptied cards as fresh spending room. The last of those is how consolidation fails in the suburbs more often than a “gotcha” clause.
The new loan may be:
- unsecured — approved on income, expenses and credit history, with no car or house attached
- secured — the lender takes security over a vehicle, a term deposit, or the home
Security usually means a lower rate and a nastier consequence if you default. Unsecured usually means a higher rate and no repossession of the house for that particular contract. Neither is automatically kinder. See responsible lending for the assessment a licensed credit provider is supposed to do before it decides the loan is not unsuitable.
ASIC’s MoneySmart material on personal loans and managing debt is the official place to start. Marketing pages that promise to “clear your debts today” are not.
When can consolidating debts help?
Consolidation can help when all of the following are true, or close to it:
- the comparison rate on the new loan is actually lower than what you are paying now, once fees are in
- the term is not so long that you pay more interest in total
- you will close or freeze the old cards, or at least cut the limits, so the debt cannot rebuild
- the repayment fits a budget you can keep in a dull month, not only in a good one
- you are not already in hardship that a variation on the existing accounts would handle more cheaply
A worked pattern, in round figures. Suppose three cards at 19.99 per cent, with minimums that barely touch principal. A five-year unsecured loan at a lower comparison rate might cut the monthly figure and a slice of interest — if you stop using the cards. Stretch the same balance over seven or ten years and the monthly figure looks even gentler while the interest bill grows. The “help” was the term, not the rate.
If repayments already will not fit, read how to ask a lender for hardship help before you add another contract. A hardship variation on the debts you have does not require a new enquiry. A consolidation loan does.
What are the risks of rolling cards into a loan?
Credit cards are expensive and flexible. A personal loan is usually cheaper per dollar and rigid. Rolling the balance across changes both the price and the shape of the problem.
Risks that show up in real files:
- You keep the cards open. The loan pays them down. A month later the supermarket and a tyre bill live on the cards again. You now have the loan and the cards. Lenders who have seen this movie will look at your credit report for exactly that pattern.
- The term is longer than the time you would have taken to clear the cards. Minimum card payments are a trap. So is a ten-year loan for a three-year spending binge.
- Fees hide in the comparison rate, or just outside it. Establishment fees, monthly fees, and “loan origination” charges matter. If you do not know what a comparison rate includes, stop and learn that before you apply.
- Early repayment of the old debts is not the same as early repayment of the new one. Some loans have break costs. Some do not. Read the contract.
- A new enquiry and a new account land on Equifax or Experian. That is not a reason to avoid a loan you have already decided, in the cold light, is cheaper. It is a reason not to apply at six lenders in a fortnight. Hard versus soft enquiries is the related explainer.
- The application is declined after the enquiries. You then have the old debts and a busier credit file. Do the homework on eligibility first.
If the point of consolidation is to “boost your score”, you are reading the wrong brochure. Scores move when the file is dull and on time. How to improve your credit score is mostly behaviour, not a product.
Why does a longer term make repayments look smaller?
Because that is how amortisation works. Stretch $18,000 over three years and the repayment is higher. Stretch it over seven and the repayment drops. The interest, unless the rate is tiny, usually rises.
Lenders know households shop with the monthly number. Comparison sites know it too. The National Credit Code and the consumer credit advertising rules push lenders to show a comparison rate for many loans precisely so the cheap-looking monthly figure is not the only number in the ad. Use it. Then ignore it long enough to calculate total repayable: all instalments plus fees, minus any genuine, written waiver.
A smaller repayment that lasts four extra years is not a discount. It is a longer rental of the same money. If your goal is to be out of the debt, shorter is usually cheaper. If your goal is to stop the account bouncing this month, a longer term can be the thing that makes the calendar work — at a price you should look at with a calculator, not with relief.
Write both numbers down: monthly, and total. If you cannot see the total in the credit guide or the loan offer, ask for it in writing. A credit provider that will not tell you the total repayable is not doing you a favour.
What is the difference between secured and unsecured consolidation?
Unsecured means the lender’s main lever, if you stop paying, is the contract, collections, a default listing, and eventually court. It cannot, on that contract alone, take the house. Rates are higher because the lender’s recovery is weaker.
Secured means you give the lender rights over an asset. Common versions:
- a car loan that refinances the car and folds in extra cash to pay cards
- a “secured personal loan” against a vehicle you already own
- a home-loan top-up or refinance that pays out cards and personal loans
The rate often looks civilised. The risk is not. Miss the car loan and the car is in play. Miss the mortgage and the house is in play. Unsecured card debt, for all its ugly interest, does not usually come with a sheriff at the front door of the property in the same way a mortgage default can.
There is a second, quieter cost. Card debt is often medium-term. Mortgage debt is long. Moving a holiday and a fridge onto a 25-year loan can bury the interest in the home-loan statement until you sell. Families in Melbourne’s north have done this for decades. Some slept better. Some discovered, at refinance, that the “cleared” cards had never been closed and the redraw was gone.
If the security is the house, the conversation is a home-loan conversation as well as a consolidation conversation. It is not something a website should bless.
When does consolidation just extend the interest?
When the new loan’s only real trick is time.
Signs the product is stretching rather than solving:
- the comparison rate is not much better than the blended rate you already pay
- the term is longer than the remaining life of the debts being paid out
- interest continues on a portion that could have been cleared with a hardship pause and a strict budget
- you are consolidating because a salesperson called, not because you ran the numbers
- there is a fee to “pay out” debts that were already close to finished
- the lender wants to secure a modest card balance against a car that is worth more than the debt
Another version: you consolidate, feel the relief of one repayment, and do not change the budget that produced the cards. How to budget when you have debt is less glamorous than a new loan and more relevant. The old co-operative site put budgeting tips beside personal loans for a reason.
Payday-style short-term credit is a particularly poor consolidation tool. The fee caps on small amount credit contracts still produce expensive money. Rolling a card into a payday loan is usually a step down in quality, not up.
How do comparison rates change the picture?
A comparison rate is designed to include the interest rate and most up-front and ongoing fees, for a stated loan amount and term. It is not a personality score. It is also not perfect. Some charges sit outside it. Some features (redraw, extra repayments, a secured versus unsecured option) do not show.
Use comparison rates to knock out the ads that look cheap because the establishment fee is huge. Then read the credit contract, the credit guide, and the repayment schedule. If two loans have similar comparison rates but one is secured against the car, they are not similar products.
ASIC has long treated comparison rates as a consumer-protection tool, not as a marketing extra. If a broker or a website will show you only the “from” rate in 48-point type, you do not yet have enough to decide.
Also compare credit card alternatives honestly. A balance transfer with a promotional period can be cheaper than a five-year loan — if you can pay it off inside the period and if the revert rate will not punish you. It can be more expensive if you only pay the minimum. Neither path is “consolidation” in the loan sense. Both can be used as if they were. Run the same total-repayable test.
What should you check before you apply?
A practical list, none of which is personal advice:
- Pull both free credit reports. Errors first; applications second.
- List every debt, rate, fee, and payout figure as at a named date.
- Write a budget that includes rent, food, fuel and the dull bills. If the new repayment only fits when you pretend those are smaller, it does not fit.
- Ask whether hardship on the existing accounts would achieve the same breathing room without a new contract.
- Get the comparison rate, total repayable, and security (if any) in writing.
- Ask what happens if you repay early.
- Ask whether the lender will pay out the old debts directly. If the money hits your transaction account, the temptation is obvious.
- Decide in advance which cards will be closed or limited, and when.
- Apply to one or two lenders you actually fit, not seven.
- If the loan is declined, or the offer is worse than the ads, do not immediately take a more expensive “second-chance” product. That is how people meet payday lenders.
If a credit provider mishandles the application, refuses to consider hardship, or the loan looks unsuitable in hindsight, the path is IDR and then AFCA — see how to complain to AFCA about a credit provider. AFCA is free for consumers. It is not a second sales desk.
The Plenty River in afternoon light is a better metaphor than the industry would like: the water is still moving even when the surface looks calm. A single repayment can be calmer. Check whether the current underneath is longer, secured, or simply the same interest with a new name. Then decide with the contract, not with the brochure. For more on this cluster of problems, the debt and hardship hub collects the related guides.
Frequently asked questions
Does a debt consolidation loan improve your credit score?
Not by itself. Closing cards and paying on time can help a file over months. A new loan adds an enquiry and a fresh account. Missed repayments on the consolidation loan will usually look worse than the mess you were trying to tidy.
Is a consolidation loan the same as a balance transfer?
No. A balance transfer moves card debt onto another card, often with a promotional period. A consolidation loan is a separate credit contract with its own term, rate and fees. Compare the comparison rate and the total repayable on both.
Should I use my home as security to consolidate credit cards?
Putting unsecured card debt onto a mortgage can cut the rate and put the house at risk if you cannot pay. That trade-off is a legal and financial one. This article cannot tell you whether it is appropriate for you.
Questions about this guide? Contact the Plenty Credit desk or read our editorial standards.
More in Debt and hardship
How to complain to AFCA about a credit provider
AFCA is the free external dispute body for most licensed lenders, card issuers and BNPL providers. You usually complain to the firm first, then lodge online with documents and dates. This is general information, not legal advice.
9 min read · 12 July 2026
What happens if you default on a loan in Australia
A missed payment is not automatically a default listing. Here is the usual path from a late repayment through collections, credit-file listings, court, and why hardship and AFCA can still matter. General information, not advice.
9 min read · 30 May 2026
Payday loans and small amount credit contracts explained
Australian payday loans are regulated as small amount credit contracts, with fee caps, a 10 per cent income test from June 2023, and comparison rates that look alarming because the term is short. General information only.
9 min read · 21 April 2026