Emergency funds in Australia: how much is enough?
Three months of expenses is a rule of thumb, not a law. High rent, existing debt and where you park the cash matter more than a round number. Buy now, pay later is not a buffer. General information only.
Published 19 March 2026 · Updated 20 October 2026 · 9 min read
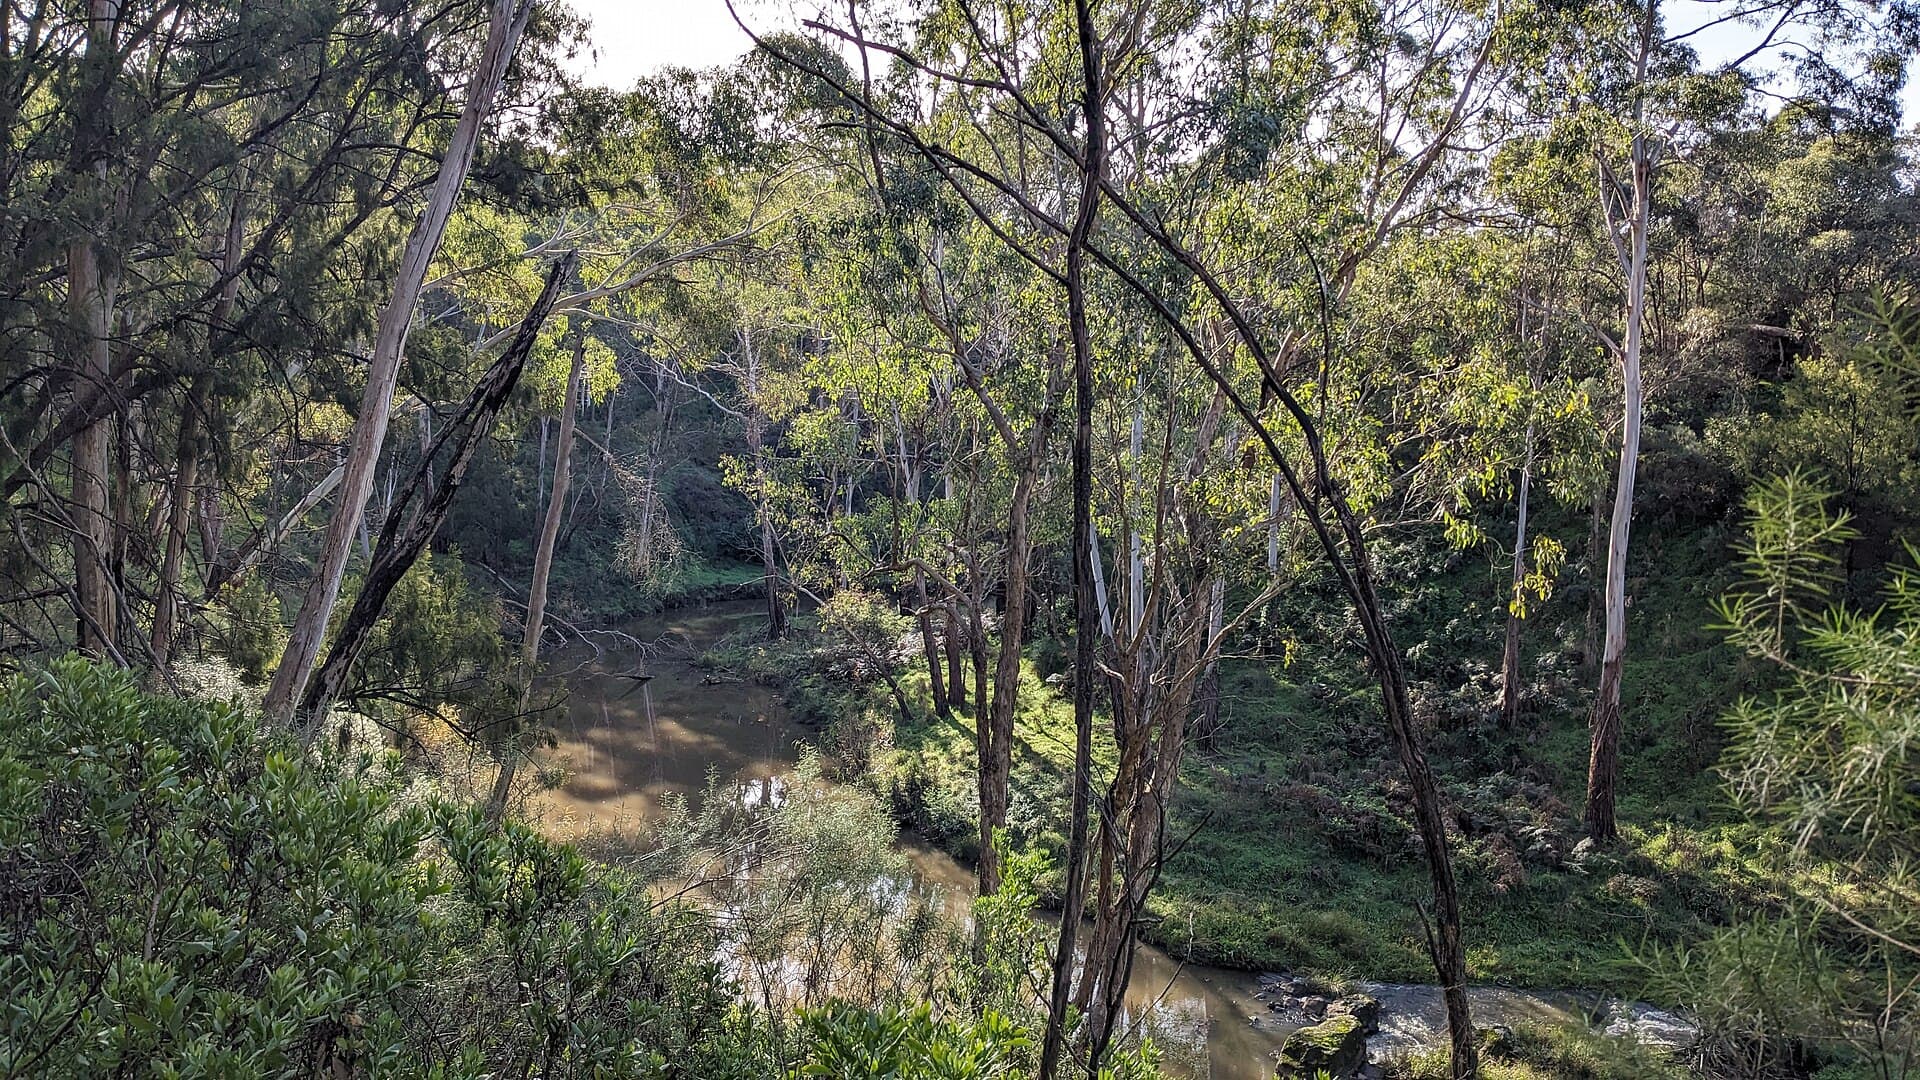
Photo: Philip Mallis. CC BY-SA 2.0. Source. See all image credits.

“Three months of expenses” is the sentence that appears on almost every Australian savings page, including useful ones. It is a rule of thumb, not a provision of the National Credit Code, and not a moral exam. For a household in South Morang paying a large share of net pay in rent, three months can look like a second bond. For a household still meeting card minimums, it can look like a fantasy that delays the first $200.
Plenty Credit’s old co-operative talked about savings and term deposits in the same breath as a budgeting calculator. The river red gums along the Plenty River are a better picture than a round number: shade is built slowly, and the useful amount is the amount that is actually there when the car fails. This is general information, not a recommendation of a target, a product, or a place to keep money.
How much emergency money do Australians actually need?
ASIC’s MoneySmart savings guidance treats an emergency fund as money that covers a shock without new debt: a broken transmission, a gap between jobs, a medical gap payment, an urgent flight. The public rule of thumb is often three months of essential expenses — not three months of your current lifestyle, and not three months of gross salary.
Essential, in this setting, is close to the list in how to budget when you already have debt: housing, food, utilities, medicine, and the transport that preserves income. Subscriptions, dining out and a planned holiday do not belong in the multiple.
What the rule of thumb cannot see:
- how stable the income is. A permanent public-sector fortnight and a casual hospitality roster are not the same risk.
- how high the housing cost is. If rent is half of take-home pay, “three months” is an enormous cash pile relative to what the household can save.
- whether debt is already compounding. A card at a high annual rate does not pause because you are theoretically saving.
- whether anyone else can help, briefly. That is a fact of the household, not a virtue.
A first target that exists — one month of essentials, or even a fortnight of rent plus a car excess — is more useful than a three-month poster you never start. MoneySmart’s own tone is to begin, then build. That is still the right tone.
Why do rules of thumb break down when rent is most of the pay?
Because the multiple is applied to a large number.
Suppose essential monthly costs are $4,200, of which $2,400 is rent. Three months is $12,600. On a remaining surplus of $80 a fortnight, that target is years away. Shame is a poor savings product. People in that position often do one of two unhelpful things: they decide the project is impossible and save nothing, or they cut groceries to a level they will not keep and then use a card at the supermarket.
A more honest sequence for a high-rent household:
- Write the essential monthly figure, not the Instagram figure.
- Set a first cash target you can reach in a defined number of fortnights — the insurance excess, a week of rent, a known car-repair number.
- Keep meeting debt minimums. An emergency fund built by missing a personal-loan debit is not a fund. It is arrears with a savings nickname.
- Only after that first target exists, decide whether the next dollars go to extra debt or to a second month of buffer.
If the surplus is zero or negative, the emergency-fund article is the wrong article for this fortnight. Financial hardship and the National Debt Helpline on 1800 007 007 are the institutions that exist for that arithmetic. You can still keep $50 in a separate account if you can; you should not pretend you are in month two of a three-month plan.
Where should you keep an emergency fund in Australia?
Somewhere you can reach without a default notice and without a break fee you cannot afford, and somewhere you will not spend because it sits next to the everyday debit card.
Common Australian places, each with a different friction:
- an at-call savings account at an authorised deposit-taking institution (ADI) — a bank, credit union or building society
- a high-interest savings account that pays a bonus rate only if conditions are met
- a mortgage offset account, if you have a home loan that offers one
- a redraw facility on a home loan, which is not the same as an offset and is not the same as a deposit
- a term deposit, which is usually the wrong home for money you might need on Tuesday
The Financial Claims Scheme — the government guarantee people mean when they say “the money is guaranteed” — generally covers deposits with an ADI up to $250,000 per account holder per ADI. It is a protection against the institution failing, not a protection against inflation or a poor rate. Our companion piece on term deposits versus high-interest savings walks through access, bonus-rate traps and that $250,000 cap.
Do not keep the entire buffer in a redraw if you would have to ask permission, wait, or risk putting the loan into a shape you do not understand. Do not keep it in shares, crypto, or a term deposit that penalises an early break unless you have a second slice of cash that is actually at call.
Is a mortgage offset better than a high-interest savings account?
It depends on the home-loan rate, the savings rate you will actually receive, and how you behave when the money is visible.
Money in a 100 per cent offset account usually reduces the balance on which the lender charges interest, dollar for dollar, while remaining yours to withdraw. If the loan rate is higher than the best savings rate you can keep without breaking bonus conditions, the interest you do not pay can be worth more than the interest you would have earned, and the earning is not taxed as deposit interest in the same way. That last point is why people like offsets. It is also why this paragraph is not tax advice.
A high-interest savings account at another ADI can still be the better operational choice when:
- you do not have a home loan, or the loan has no genuine offset
- you would spend the offset because it looks like “spare” money in the banking app
- the bonus savings rate, honestly met, beats the loan rate (uncommon, but possible in odd rate cycles)
- you want the emergency fund institutionally separate from the mortgage, so a future refinance conversation is cleaner
Redraw is a cousin, not a twin. Redraw is usually your extra repayments sitting against the loan. Access rules, minimum redraw amounts, and the lender’s right to vary the facility live in the contract. Read them. An emergency fund you cannot withdraw on the day you need it is a marketing label.
Whatever you choose, write down the conditions. A savings account that drops from a advertised bonus rate to a base rate the month you withdraw is still a valid home for a buffer — you just should not count the bonus in the plan.
Why is buy now, pay later not an emergency fund?
Because it is credit. An emergency fund is a sum you already hold.
Buy now, pay later can look like a buffer at the checkout. It is an agreement to pay later, often in instalments, with late fees and, under the low cost credit contract regime that commenced in June 2025, a clearer path into hardship, AFCA and credit reporting. Using BNPL when the fridge fails adds a new due date to a month that already failed. It does not replace the fridge-and-rent problem with a solved problem.
The same sentence applies to a credit-card limit you have not used yet. An unused limit can be a last resort. It is not a fund. Interest, cash-advance pricing, and a hard look at utilisation all still apply. A payday loan is a worse last resort: a small amount credit contract is expensive by design.
If the shock has already arrived and there is no cash, the honest tools are the ones in the debt and hardship guides: talk to the existing lenders, ask for time, use the National Debt Helpline. Opening a new facility to simulate a savings account is how files acquire clustered enquiries.
How do you start a buffer when you already have debt?
You start small, and you do not skip the minimums to do it.
A workable order, which matches the budgeting article:
- Essentials.
- Every contractual minimum.
- Hardship letters where the minimums will not fit.
- A tiny separate balance — even $20 a fortnight — with a name that is not “spending”.
- Extra to the dearest debt, or to the next buffer milestone, as a conscious choice rather than a mood.
Some households will correctly send almost every surplus dollar to a high-rate card for a year and keep only a thin emergency slice. Others will feel safer with one month of rent parked before they accelerate the card. There is no Plenty Valley certificate for picking the optimal split. There is a cost to having zero cash: the next shock becomes new credit.
Automate the small transfer on payday if you can. Keep the account at a different ADI, or at least behind an extra login, if looking at it causes it to vanish. Review the target when rent changes, when hours change, and after any hardship arrangement ends.
What counts as an emergency, and what does not?
An emergency is a cost that is unplanned, necessary, and time-sensitive: the car that gets you to remaining work, a medical gap, a security bond when you must move, a funeral, a sudden loss of hours.
It is not a sale. It is not a wedding deposit you agreed to in January. It is not replacing a working phone because the screen has a chip. Using the fund for those things is how a buffer becomes a second everyday account.
When you do use it for a real emergency, the job is to rebuild it, not to narrate the withdrawal as a failure. Write the new target. Adjust the fortnightly transfer. If the emergency has also broken the debt calendar, write the hardship letters in the same week. The co-operative newsletter would have ended on that practical note. So does this one.
Related guides sit under saving and budgeting. If the question is where a larger, longer-term sum belongs, read term deposits versus high-interest savings accounts next. If the question is whether this month closes at all, start with the budget and the Helpline, not with a three-month slogan.
Frequently asked questions
How much should an emergency fund be in Australia?
A common rule of thumb is three months of essential expenses. That figure is a starting point, not a requirement. Households paying high rent, carrying debt, or with uneven hours may need a smaller first target they can actually reach.
Should I keep emergency money in an offset account or a savings account?
An offset can reduce home-loan interest while remaining accessible. A high-interest savings account can pay a deposit rate, sometimes with bonus conditions that punish a withdrawal. Match the product to how quickly you might need the cash.
Can I use buy now, pay later as an emergency fund?
No. BNPL is credit. It creates instalments, possible late fees and, under the current rules, a path onto a credit file. A buffer is money you already have.
Questions about this guide? Contact the Plenty Credit desk or read our editorial standards.
More in Saving and budgeting
Term deposits vs high-interest savings accounts
A term deposit usually pays a fixed rate for a locked period. A high-interest savings account stays at call, often with a bonus rate you can lose. Access, break costs and the $250,000 government guarantee all matter. General information, not advice.
9 min read · 25 April 2026
How to budget when you already have debt
When debt is already on the statement, the useful order is essential bills, then contractual minimums, then hardship if those will not fit, and only then extra repayments. General information, not personal advice.
9 min read · 16 February 2026