Term deposits vs high-interest savings accounts
A term deposit usually pays a fixed rate for a locked period. A high-interest savings account stays at call, often with a bonus rate you can lose. Access, break costs and the $250,000 government guarantee all matter. General information, not advice.
Published 25 April 2026 · Updated 20 October 2026 · 9 min read
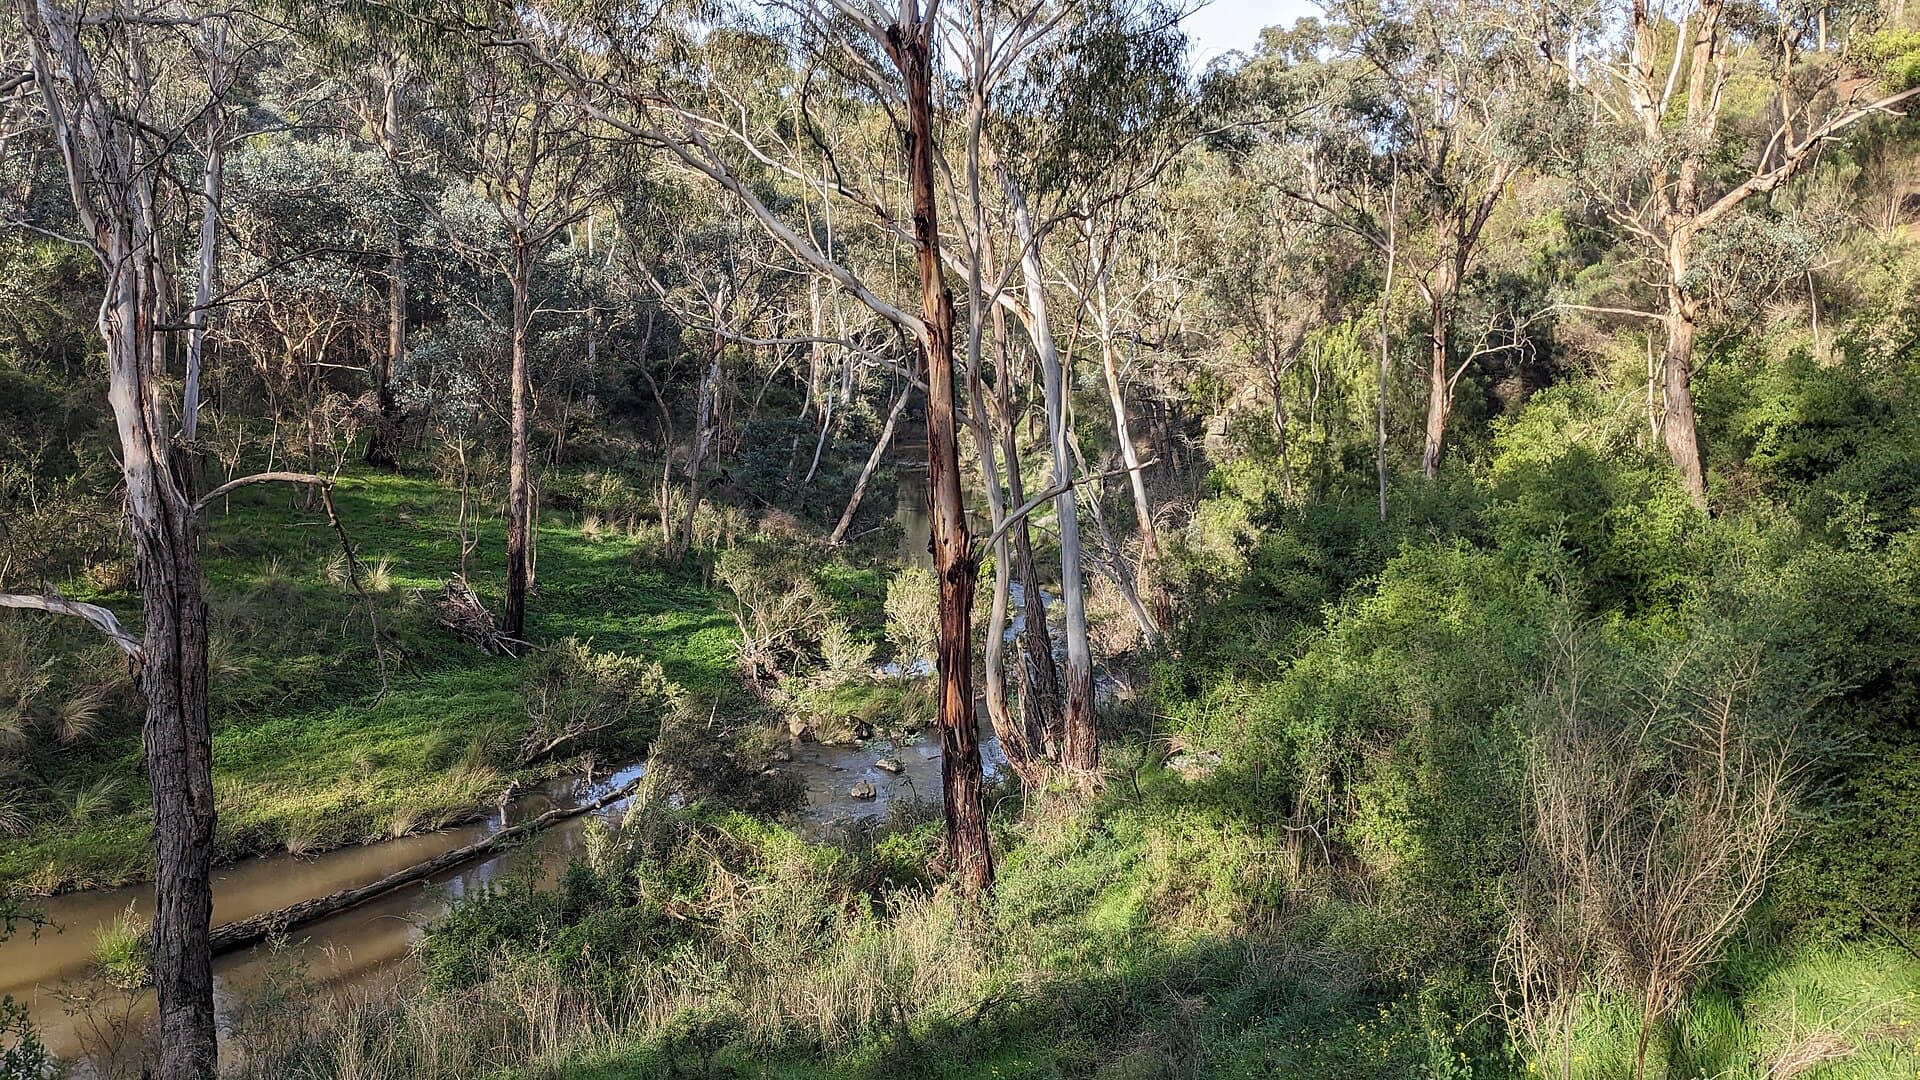
Photo: Philip Mallis. CC BY-SA 2.0. Source. See all image credits.

A term deposit and a high-interest savings account are both ways of leaving money with an authorised deposit-taking institution. They are not the same product. One usually locks a rate and the cash. The other usually keeps the cash at call and makes the rate conditional — on a monthly deposit, on no withdrawals, on a balance cap, or on a “bonus” period that expires.
The old Plenty Credit Co-operative listed term deposits among ordinary member products, next to a savings conversation that never pretended a poster rate was the whole story. Bushland along the Plenty River in South Morang is a fair metaphor only if you remember that a locked gate and an open path are different walks. This guide is general information. It is not a recommendation of any ADI, term, or account.
What is the real difference between a term deposit and a high-interest savings account?
A term deposit is a contract to leave a sum with an ADI for a stated period — commonly one month to five years — in return for a fixed interest rate (or a clearly described stepped rate). You typically cannot add and subtract at will. At maturity you decide whether to roll the deposit, take the money, or move it. ASIC’s MoneySmart term deposit page is the official explainer to keep open.
A high-interest savings account is usually an at-call deposit. You can withdraw. The rate is often variable, and the advertised number is frequently a bonus rate stacked on a low base rate. MoneySmart’s broader saving guidance treats these accounts as useful when you will meet the conditions and as disappointing when you will not.
In one sentence: the term deposit sells certainty of rate and buys illiquidity. The savings account sells access and often buys conditions.
Other differences that matter on a kitchen table in the Plenty Valley:
- Interest calculation. Term deposits usually pay at maturity or at set intervals. Savings accounts usually accrue daily and credit monthly. The calendar affects how you compare two advertised percentages.
- Top-ups. Many term deposits do not accept extra deposits during the term. Savings accounts do.
- Who the product is for. Money you might need for an emergency wants access. Money you will not touch until a known date — a tax bill in April, a bond in November — can tolerate a lock.
When does a higher rate stop being useful?
When you cannot keep the money in the product for the period the rate assumes.
A term deposit at 4.8 per cent for twelve months is not “higher” than a savings account at 4.5 per cent if you break the deposit in week six and receive a reduced rate that works out worse, plus friction. A savings account at 5.0 per cent bonus is not higher than 4.2 per cent if you miss the monthly deposit condition eight times a year and spend most of the year on the 0.5 per cent base.
Compare, on paper:
- the rate you will actually receive, not the headline
- the fees (monthly account fees are less common than they were; they have not vanished)
- the access rules
- the tax treatment of interest (interest on deposits is generally assessable; this is not tax advice)
- whether the money is part of a household that still has debt at a higher rate than either deposit
That last point is the one people skip. Extra cash sitting in a 4 per cent savings account while a card compounds at a much higher annual rate is a choice, not a law of nature. Sometimes it is the right choice — a thin emergency fund should exist — and sometimes it is inertia. How to budget when you already have debt is the order of operations; this page is only the parking question.
What happens if you break a term deposit early?
You ask the ADI to release the money before maturity. The institution will point you to its early-withdrawal rules. Typical Australian patterns, which you must still verify on the product in front of you, include:
- a notice period (often 31 days) before the funds are released
- a reduction in the interest rate for the period the money was actually held
- a break fee, or an interest adjustment that functions like one
- a refusal to allow a break except in defined circumstances, on some products
You generally receive the principal back. You should not assume you receive the advertised interest. In a rising-rate world, breaking to re-deposit at a higher rate can still be rational after the penalty. In a falling-rate world, the lock was the product you bought.
Read the pre-contractual information before you treat a term deposit as a slightly awkward savings account. If the household’s risk is a lost job or a car failure, a break-fee product is a poor home for the only cash. Split the money if you need both a locked rate and a buffer.
If the ADI is slow, unclear, or applies a cost that does not match the terms, use its internal complaints process and, if needed, AFCA. Deposit products of ADIs sit in AFCA’s world. A complaint is not a way to invent a better rate. It is a way to have the contract applied.
How do bonus-rate savings accounts actually work?
They advertise a number you earn only if you behave like the marketing department hoped.
Common conditions:
- deposit a minimum amount each month
- make no withdrawals, or no more than a set number
- keep the balance below a cap (bonus rates often die above $50,000, $100,000 or another threshold)
- be a new customer, or hold a linked transaction account
- accept that the bonus is introductory and reverts after a few months
The base rate underneath can be close to nothing. Missing one condition for one month can drop the month’s interest sharply. That is not a trick hidden in six-point type only. It is usually in the large type as “bonus”. Households still plan as if 5.00 per cent were a fixture.
A practical way to use these accounts:
- put emergency money in an account whose conditions you can meet even in a bad month, or accept that a withdrawal will cost you the bonus and still keep the money there for access
- put sinking funds (rego, insurance, Christmas) in an account if the monthly deposit condition matches payday
- do not open five bonus accounts in a fortnight to chase introductory rates if the administrative load means you will miss conditions and if any application path leaves a mark you do not want. Deposit accounts are not credit contracts, but linked products and cross-sell can become credit applications if you are not paying attention
Variable rates also move when the Reserve Bank moves, and sometimes when it does not. A term deposit’s virtue is that the rate you accepted is the rate for the term. A savings account’s virtue is that you can leave.
What does the $250,000 government guarantee cover?
The Financial Claims Scheme (FCS), administered with APRA, is a government guarantee of deposits with authorised deposit-taking institutions. In outline, it covers up to $250,000 per account holder per ADI.
That sentence has several moving parts:
- Per ADI, not per account. Three savings accounts at the same bank still sit under one $250,000 cap for that holder at that institution.
- Per account holder. A single name and a different single name at the same ADI are different holders. Joint accounts have their own treatment — typically the cap applies to each named holder’s share, but you should read the current FCS material rather than guess on a large joint sum.
- Deposits. Term deposits and ordinary savings balances at an ADI are the core of what people mean. Some products that look like “cash” are not deposits with an ADI.
- Not a rate guarantee. The FCS does not promise you 5 per cent. It is about getting protected deposits back if the institution fails.
- Not a credit-file concept. It has nothing to do with Equifax or Experian.
If a household’s cash plus term deposits at one ADI exceed $250,000, the ordinary conversation is whether to spread amounts across separately licensed ADIs. That is a diversification question, not a Plenty Credit product pitch. Foreign-owned banks that are ADIs in Australia are still ADIs. Non-ADI investment platforms that “hold cash” may not be. Read the fine print; MoneySmart and APRA are the public sources.
Offset balances and redraw sit next to this topic. Money in a genuine deposit offset is generally still a deposit with the ADI. Redraw is extra repayments against a loan. Do not assume the FCS sentence you used for a term deposit applies, without looking, to every balance in a home-loan app.
How should an emergency fund sit next to a term deposit?
The emergency fund wants access. The term deposit wants time. They can coexist. They should not be the same pile.
A pattern that matches the emergency fund guide:
- keep a first slice at call — enough for a known shock — in a savings account whose conditions you understand
- only then lock a second slice you will not need before maturity
- ladder term deposits (staggered maturities) if you want some money becoming available every few months without breaking anything
- do not lock the rent money
If you have a mortgage offset that genuinely reduces interest and stays withdrawable, that offset may do the job of the at-call slice. If withdrawing from offset would cause you problems with the loan, it is not an emergency fund. It is a loan feature you have misunderstood.
Which product fits a household that still has debt?
Sometimes neither, beyond a thin buffer.
If a credit card, a personal loan or a small amount credit contract costs more than you can earn on a deposit, extra dollars have a higher “return” as repayment than as savings interest. That is arithmetic, not a sermon. A household can still choose a small cash reserve so the next shock does not become another contract. Budgeting when you already have debt is that conversation.
Do not open a term deposit with money you will need for the next personal-loan debit. Do not chase a bonus savings rate by holding a balance you should have sent to a collector you have already agreed to pay. Do not treat a new credit product — a card with a “savings” companion account, a balance transfer, a consolidation loan — as a deposit strategy.
If the ADI’s terms are unclear before you sign, you are allowed to walk away. Deposit contracts are simpler than consumer credit contracts, but they are still contracts. The co-operative that once printed rates on a branch flyer expected members to ask how to get the money out. That question is still the first one.
More guides in this series live under saving and budgeting. If the cash does not exist yet, start with the budget and, if needed, hardship, not with a comparison of locked rates.
Frequently asked questions
Is a term deposit better than a high-interest savings account?
It is better when you can leave the money untouched for the whole term and you value a known rate. It is worse when you might need the cash early, because breaking the term can mean notice, reduced interest or a fee. Compare access first, then the rate you will actually keep.
What happens if I break a term deposit early?
Most ADIs require notice and reduce the interest, charge a break fee, or both. You usually still get your principal back. Read the specific product terms before you treat the money as available next week.
How does the $250,000 government guarantee work?
The Financial Claims Scheme generally protects deposits with a single authorised deposit-taking institution up to $250,000 per account holder. It is per ADI, not per account. Joint accounts and sums above the cap need a separate look.
Questions about this guide? Contact the Plenty Credit desk or read our editorial standards.
More in Saving and budgeting
Emergency funds in Australia: how much is enough?
Three months of expenses is a rule of thumb, not a law. High rent, existing debt and where you park the cash matter more than a round number. Buy now, pay later is not a buffer. General information only.
9 min read · 19 March 2026
How to budget when you already have debt
When debt is already on the statement, the useful order is essential bills, then contractual minimums, then hardship if those will not fit, and only then extra repayments. General information, not personal advice.
9 min read · 16 February 2026